A raise means your gross pay goes up — but your take-home pay almost never rises by the same dollar amount. Taxes take a bigger bite in absolute terms, some deductions scale up automatically, and a few costs stay completely flat. None of that means the raise "wasn't worth it" — it means the math is more layered than a straight percentage increase.
- A raise cannot shrink your paycheck through bracket math — only the income above a bracket threshold is ever taxed at the higher rate, never your whole salary.
- Percentage-based deductions, like a 401(k) set at a fixed percent of pay, automatically take a bigger dollar amount once your pay rises.
- Flat-dollar deductions, like most health insurance premiums, usually don't move at all — so more of the raise flows through on that line.
- Social Security tax stops once your year-to-date earnings cross an annual cap ($184,500 in 2026), which can change how a raise affects your very last paychecks of the year.
- Lifestyle creep — spending scaling up alongside income — is normal and human, not a moral failing, but it's worth being a deliberate choice rather than a default.
The myth: "my raise bumped me into a higher bracket, so I lost money"
This is one of the most common misunderstandings about paychecks, and it's worth killing clearly: a raise can never reduce your take-home pay because of tax brackets. It's mathematically impossible under how the U.S. graduated bracket system works.
Here's the mechanism, as described by the IRS:
- Income is taxed in layers, or tax brackets
- Each bracket's rate applies only to the slice of income that falls inside that bracket — not to your entire salary.
- If a raise pushes part of your income into a new, higher bracket, only that specific slice is taxed at the higher rate. Every dollar below the threshold keeps being taxed exactly as it was before.
So crossing into a higher bracket can never cost you money overall. At worst, the extra raise dollars are taxed at a higher rate than your other dollars — but even then, they're taxed at less than 100%. You always keep more than you had before the raise. The rate that matters here is your marginal tax rate, and it's different from your effective tax rate, which is what actually describes your overall tax burden.
Key point
Brackets alone can't make a raise cost you money. What can is different machinery: income-based benefits and credits that phase out or stop at set income levels (marketplace health insurance subsidies, some child-care and housing assistance), and, on a single check, withholding that doesn't match what you actually owe. If your income sits near one of those lines, that's where the real math is.
What actually changes when your salary goes up
A raise flows through several separate systems before it reaches your bank account, and each one behaves differently.
Federal and state income tax withholding
- Employers withhold estimated income tax from each paycheck based on the Form W-4 on file, as described by the IRS.
- A raise increases the dollar amount withheld roughly in proportion to the raise — plus a bit more if part of the raise lands in a higher bracket, but only on that slice, as covered above.
- Withholding is an estimate, not the final tax bill — it's reconciled at filing time, and being over- or under-withheld doesn't change how much tax is actually owed for the year.
FICA: Social Security and Medicare
Most paychecks also show FICA withholding, per the IRS's overview of employment taxes:
- Social Security tax applies at a statutory rate up to an annual wage base, which the Social Security Administration updates annually — $184,500 for 2026.
- Once year-to-date wages cross that cap, Social Security withholding stops entirely for the rest of the calendar year — so a raise late in the year can sometimes coincide with a paycheck where more comes home, simply because the cap was reached.
- Medicare tax has no equivalent cap — it applies to all wages, and steps up by an extra 0.9% once your wages at a job pass $200,000 in a year (IRS Topic 560).
Percentage-based deductions scale automatically
If a 401(k) contribution — or any other deduction — is set as a percentage of pay rather than a flat dollar amount, it recalculates itself every time gross pay changes. A raise means a bigger paycheck feeds a bigger contribution automatically, with no action required.
Benefit premiums usually don't move
Most health insurance premiums, life insurance deductions, and similar flat-dollar benefit costs are set at a fixed amount, not a percentage of salary. That means:
- These lines typically stay exactly the same after a raise.
- More of the raise flows through to take-home pay on this front, compared with the percentage-based lines above.
- The exception is anything explicitly structured as a percentage of pay, which is less common for benefits than for retirement contributions.
Why the first raised paycheck can look off
The first check after a raise is often the strangest one of the year. Common reasons:
- Proration. If the raise started mid–pay period, that check mixes old and new rates.
- Retro pay. Back pay for a raise that was effective weeks ago is usually treated as supplemental wages, which employers can withhold at a flat 22% federal rate (IRS Publication 15, 2026). That can make one check look heavily taxed — it's withholding, not your final tax.
- Everything percentage-based jumps at once. 401(k), HSA percentages, and any state tax all recalculate on the same check.
An example with real numbers
Illustrative numbers, using 2026 federal rules.
Assumptions:
- A single filer's salary rises from $90,000 to $95,000 (a $5,000, or about 5.6%, raise), paid biweekly.
- After the 2026 standard deduction ($16,100) and pre-tax benefits, taxable income goes from about $63,300 to $68,000 — entirely inside the 22% bracket (taxable income from $50,400 to $105,700 for single filers, per the IRS).
- FICA is assumed at a combined 7.65% (Social Security + Medicare), and the person's total wages stay under the wage base cap all year.
- 401(k) contribution is set at 6% of pay (percentage-based).
- Health insurance premium is a flat $200/paycheck, pre-tax, unchanged by the raise.
- No state income tax is modeled, to keep the math simple.
Rough math on the $5,000 raise:
| Line item | Formula | Approx. amount |
|---|---|---|
| 401(k) (6% of raise) | $5,000 × 6% | −$300 |
| Federal income tax | ($5,000 − $300) × 22% | −$1,034 |
| FICA | $5,000 × 7.65% | −$382.50 |
| Health insurance premium | flat, unchanged | $0 |
| Net increase in take-home pay | ≈ $3,283.50 |
So here, about 66% of the $5,000 raise shows up as extra take-home pay — roughly $126 more per biweekly check. Note the 401(k) is pre-tax, so income tax only hits $4,700 of the raise, not $5,000. And that $300 isn't gone; it's in your retirement account. Counting it, you keep about $3,583.50, or 72% of the raise. The health insurance line, being flat, doesn't shrink the raise further. State and local taxes (a state income tax would take another slice), filing status, and benefit elections all move the result.
Lifestyle creep: where the extra money quietly goes
Lifestyle creep is one reason a raise can feel invisible even after it clears payroll. It's not a character flaw — it's a predictable pattern:
- A slightly bigger paycheck often coincides with small, easy upgrades — a nicer lunch, a subscription, a bit less price-checking.
- Each individual choice feels minor, which is exactly why the combined effect is easy to miss.
- Without a specific plan for the new money, spending tends to expand to meet it, quietly, one convenience at a time.
There's no verdict to pass here — spending more as income grows is a completely normal response, and plenty of that spending genuinely improves quality of life. The only thing worth noticing is whether it happened on purpose or by default.
Deciding where the new money goes
Because a raise touches taxes, retirement contributions, and take-home pay all at once, it can help to look at the net increase — not the headline raise number — when deciding what to do with it. Common directions people consider, without any one being inherently "correct":
- Building or topping up an emergency fund, especially if the current cushion feels thin.
- Paying down higher-interest debt, where the math and stress relief often both point the same direction.
- Increasing retirement contributions further, beyond whatever the percentage-based bump already added.
- Directing part of it toward a specific goal, like a house down payment or a big purchase, while still allowing some of it to simply raise day-to-day comfort.
- Letting some of it absorb into lifestyle, deliberately, as a conscious trade-off rather than an accident.
Many people find it useful to decide on a split — for example, a portion toward savings or debt, a portion toward spending — before the new, larger paycheck normalizes, since it's easier to direct money before it's already blended into a routine.
FAQ
Can a raise ever actually shrink my take-home pay?
It's uncommon, but it can happen if the raise pushes household income past a cutoff for an income-based benefit or tax credit. Those cliffs work differently from ordinary tax brackets, which only tax the income above the threshold at the higher rate.
What's the difference between my tax bracket and my effective tax rate?
Your tax bracket (marginal rate) is the rate on your next dollar of income; your effective rate is your total tax divided by your total income, and it's always lower unless all your income sits in the lowest bracket. The IRS explains how the graduated bracket structure works.
Why did my 401(k) contribution amount change without me doing anything?
If your contribution is set as a percentage of pay rather than a flat dollar amount, it automatically recalculates every time your gross pay changes, including after a raise.
Does Social Security tax ever stop coming out of my paycheck?
Yes — Social Security tax stops once your earnings pass an annual wage base ($184,500 in 2026, per the Social Security Administration). Medicare tax has no such cap.
Can I change how much tax is withheld after a raise?
Withholding is controlled by the Form W-4 on file with your employer, and it can be adjusted at any time if too much or too little is being withheld. See the IRS withholding page for details.
Related reading
Pre-tax vs post-tax payroll deductions: what's the difference?
A $200 pre-tax deduction doesn't cost you $200 of take-home pay — but it doesn't disappear from the IRS's radar forever either. Here's how each bucket actually works.
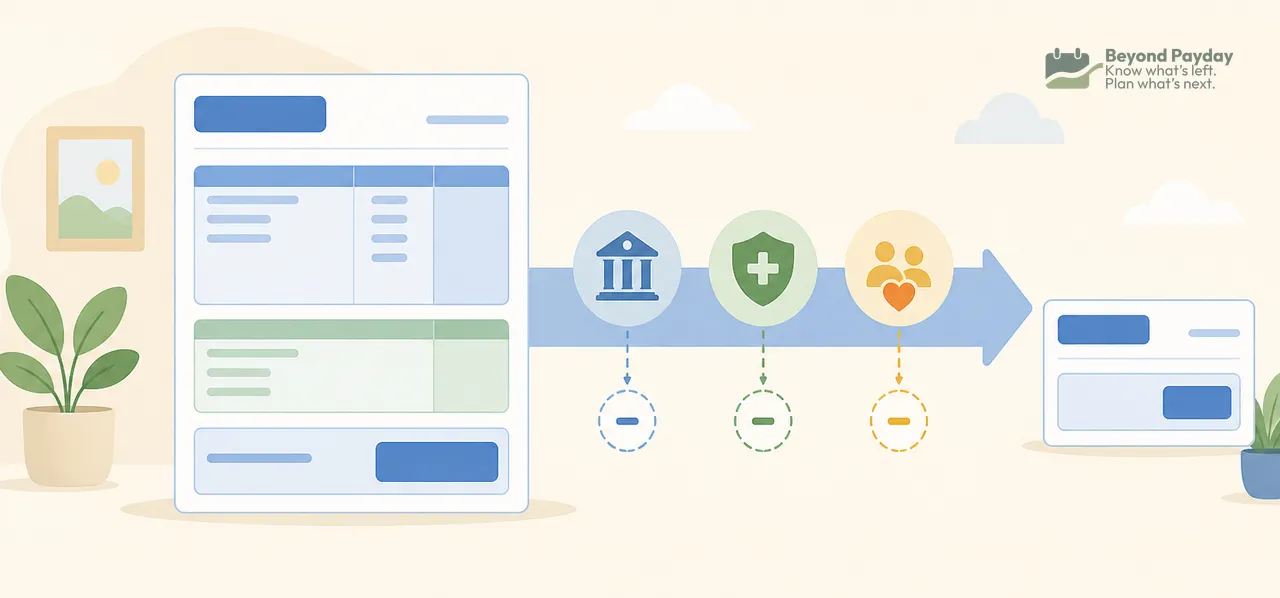
Why is my paycheck so much smaller than my salary?
Your salary is a yearly number; your paycheck is what's left after taxes and benefits come out of each pay period. Here's a line-by-line walk from gross pay to net pay, so nothing on your stub is a mystery.
W-2 vs 1099: what actually lands in your bank account
A $70,000 salary and a $70,000 1099 rate are not the same money. The surprise: after the 2026 tax math, the tax gap is small — it's the benefits that cost you.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.