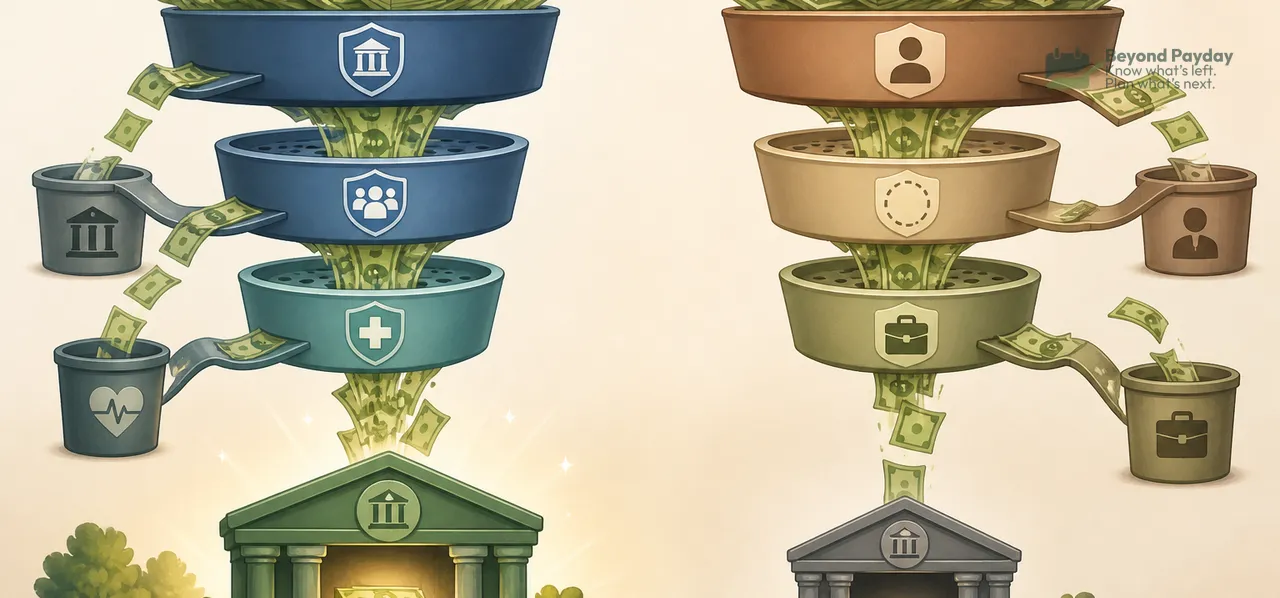
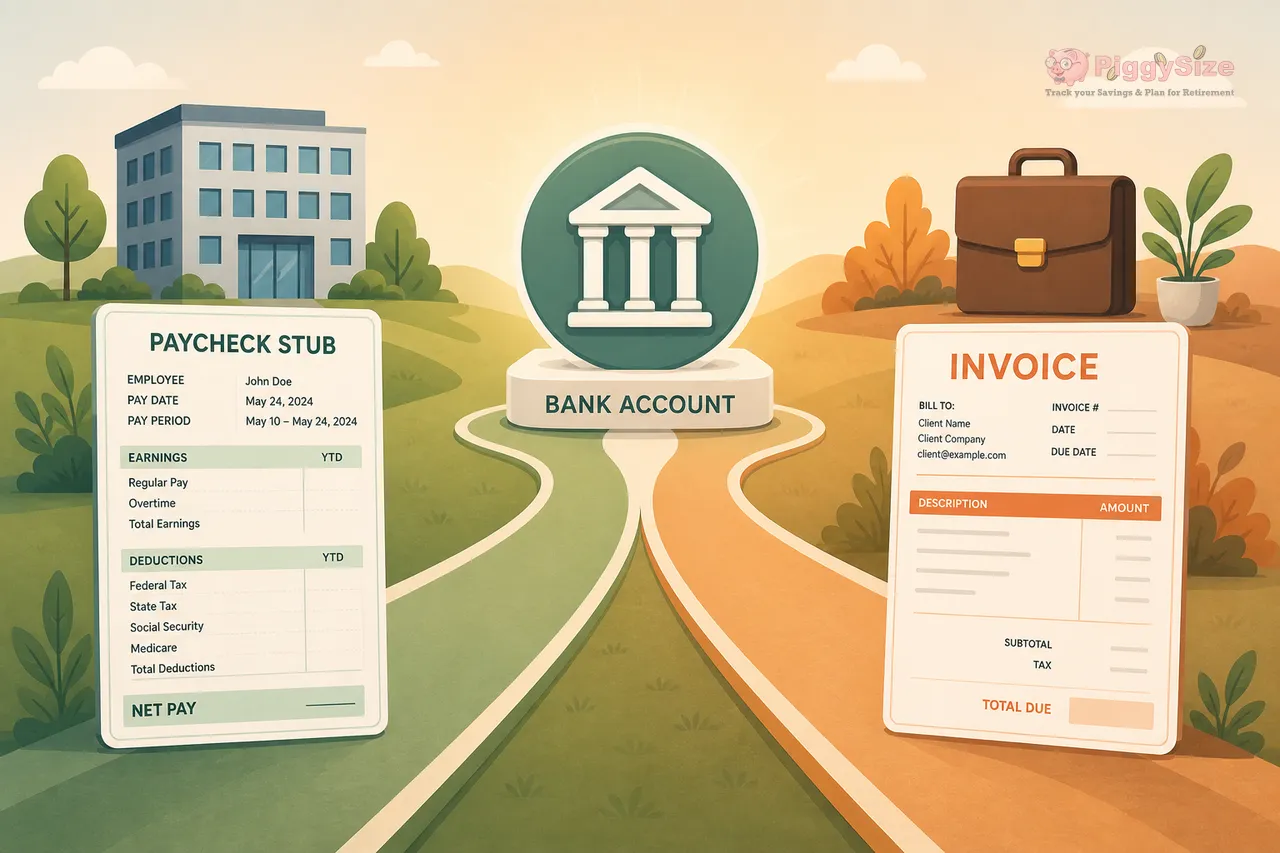
A $70,000 W-2 salary and a $70,000 1099 contract are not the same $70,000. The salary comes with an employer paying half your Social Security and Medicare tax and, often, most of your health insurance. The contract is the full amount you bill. Nothing is withheld, there are no benefits, and business costs still come out of it. The part most people get backwards: once the math is done, the tax gap is fairly small — the benefits gap is the big one.
- Self-employment tax is 15.3% on 92.35% of net profit. That covers both halves of Social Security and Medicare, versus the 7.65% withheld from a W-2 paycheck (IRS, 2026).
- The tax gap is smaller than it looks. Deducting half of that tax, plus a 20% deduction on business profit, wins much of it back. In the 2026 example below, a $70,000 contract takes home about $2,400 less than a $70,000 salary.
- Benefits are the real gap. Benefits make up about 30% of what private employers spend on pay and benefits, per the Bureau of Labor Statistics (June 2026).
- 1099 income has no withholding, so the IRS generally expects you to pay tax four times a year once you'll owe $1,000 or more.
- In the example, a contract around $86,000–$91,000 lands in the same place as a $70,000 salary with typical benefits — roughly 20–30% higher. The right gap depends on which benefits you're actually replacing.
The tax difference: who pays what
Both W-2 employees and 1099 contractors pay into Social Security and Medicare. The difference is who writes the check.
- W-2 employee: you pay FICA of 7.65% (6.2% Social Security + 1.45% Medicare), withheld from each paycheck. Your employer pays a matching 7.65% on top, out of its own pocket, per the IRS.
- 1099 contractor: you pay self-employment tax of 15.3% on 92.35% of net profit. The IRS trims profit by 7.65% first, to mirror the deduction an employer gets for its half. The result is about 14.1% of every profit dollar. It applies once net earnings reach $400, per IRS Topic 554.
- The Social Security part has a cap. The 12.4% only applies to the first $184,500 of combined wages and self-employment earnings in 2026, per the Social Security Administration. The 2.9% Medicare part has no cap, and an extra 0.9% kicks in above $200,000 (single) or $250,000 (married filing jointly).
Two deductions then shrink the contractor's income tax bill:
- Half of self-employment tax is deductible when figuring income tax. This mirrors how an employer deducts its half.
- The qualified business income (QBI) deduction lets many sole proprietors deduct up to 20% of their net profit. W-2 wages don't get it. The 2025 tax law made it permanent, per the IRS.
Note
Rates and thresholds above are for tax year 2026 and change yearly. Your own return depends on filing status, other income, deductions, and state — a CPA or enrolled agent can run the specifics.
No withholding means estimated payments
A W-2 paycheck has federal income tax (and often state tax) taken out before it lands, based on your Form W-4, as the IRS explains. A 1099 payment arrives whole.
- Individuals generally must pay estimated tax if they expect to owe $1,000 or more when they file, per the IRS.
- 2026 due dates: April 15, June 15, and September 15, 2026, and January 15, 2027.
- Skipping them doesn't skip the tax. The bill still comes due in April, and the IRS can add a penalty for paying late. That's why many contractors move a fixed share of every payment into a separate account the day it arrives. (More on sizing that share: how much to set aside for 1099 taxes.)
Deductible expenses: where 1099 has a real edge
Self-employment isn't only extra cost — it opens doors W-2 pay doesn't. Self-employed workers can deduct ordinary and necessary business expenses, per the IRS.
- Business costs — supplies, software, equipment, business mileage, a qualifying home office — lower the profit that both income tax and self-employment tax are figured on.
- Health insurance premiums you pay yourself are generally deductible when figuring income tax, if you weren't eligible for an employer-subsidized plan (through your own job or a spouse's).
- Bigger retirement limits. A solo 401(k) lets you contribute as both employee (up to $24,500 in 2026) and employer, up to a $72,000 combined cap — room a W-2 worker only gets if their employer is generous.
- W-2 employees mostly can't do this. Most employees can't deduct work costs their employer doesn't pay back on their federal return at all.
Benefits: what an employer quietly covers
A salary figure rarely describes the whole paycheck. Across private industry, benefits run about 30% of what employers spend on pay and benefits: $14.07 of every $46.89 per hour worked, according to the Bureau of Labor Statistics (June 2026 data, released September 2026). Put another way, for every $1 of wages, employers spend about 43 cents more on benefits.
| Often included for W-2 employees | Usually the contractor's own responsibility on 1099 |
|---|---|
| Employer-sponsored health insurance | Buying health coverage independently |
| Employer's matching share of Social Security/Medicare | Covering both shares via self-employment tax |
| Employer retirement plan contributions/matching | Self-funding retirement savings entirely |
| Paid time off and paid holidays | Unpaid time off — no income when not working |
| Unemployment insurance coverage | Generally not eligible for unemployment if work dries up |
| Workers' compensation coverage | Often no equivalent coverage |
Health insurance is usually the biggest line. In 2025, the average employer plan cost $9,325 a year for single coverage, with workers paying $1,440 of it — so the employer covered about $7,885. For family coverage, it was $26,993 with workers paying $6,850, according to the KFF Employer Health Benefits Survey (2025).
Not every W-2 job offers all of this. But where it exists, it's real money a like-for-like comparison has to price in.
::img{src="https://wzasepcagchvirlttomb.supabase.co/storage/v1/object/public/blog/optimized/53790030-02f4-4edc-a66d-044ed8467d06.webp" alt="Woman in green shirt organizing receipts into an "expenses" folder at wooden desk, surrounded by potted plants, a pink piggy bank, health insurance card, calendar, desk lamp, and bookshelf." width=800 height=800 size=inline}
Why the "1099 rate should be higher" rule of thumb exists
A common rule of thumb says a contract rate needs to be meaningfully higher than a salary to match it. The gap comes from stacking four things:
- The extra payroll tax. The employer's 7.65% becomes yours, softened by the two deductions above.
- The benefits. Health premiums, retirement matching, and paid time off, priced out one by one.
- Minus deductible business expenses. Real business costs shrink the income you're taxed on, which a salary can't do.
- Plus the lack of a safety net. No unemployment insurance, no paid sick days, and uneven work. Many contractors add a cushion to their rate for this.
That's why no single multiplier fits everyone:
- Benefit generosity varies enormously. Leaving a job with rich family coverage and a 6% match needs a far bigger gap than leaving one with neither.
- Expense levels vary by profession. A contractor with heavy equipment costs nets less of each dollar billed.
- Stability matters. Steady 1099 work at a slightly lower effective rate can beat sporadic work with long gaps.
Worked example: $70,000 salary vs. $70,000 contract (2026)
Illustrative and simplified.
Assumptions: single filer, 2026 federal rules, standard deduction ($16,100), no state income tax, no business expenses, no other income.
| W-2 at $70,000 | 1099 at $70,000 | |
|---|---|---|
| Social Security + Medicare you pay | $5,355 | $9,891 |
| Federal income tax | $6,570 | $4,452 |
| Take-home before benefits | $58,075 | $55,658 |
The contractor pays about $4,500 more in Social Security and Medicare tax. But deducting half of it, plus the QBI deduction, cuts their income tax by about $2,100. Net gap: about $2,400 a year, or about $200 a month.
Now price in what the salary was quietly carrying:
- To match take-home only: a contract of about $73,100.
- To also buy health coverage costing what the average employer contributes ($7,885, per KFF 2025) and replace a 4% retirement match (the employer adding 4% of salary, $2,800, to a 401(k)): about $85,700. Both costs are deductible for the contractor, which is why this isn't simply $73,100 + $10,685.
- To also take three weeks off unpaid, billing 49 weeks instead of 52: about $90,900 — roughly 30% above the salary.
Real individual-market premiums vary widely by age, state, and plan, so the health line alone can swing this by thousands.
Classification isn't a choice — it's based on the facts
A common misconception is that a worker or business can simply pick 1099 because it's convenient or because the contract says so.
- Classification turns on the facts of the working relationship — chiefly who controls what work is done and how — per the IRS.
- A "contractor" label in a contract doesn't settle it if the actual relationship looks like employment.
- The IRS, the U.S. Department of Labor, and many states each apply their own tests, and some state tests are stricter than the IRS's.
- Misclassification has consequences for both sides. A worker who thinks they've been misclassified can ask the IRS to decide, using Form SS-8.
Once you know roughly what's landing in your account each month — a steady W-2 paycheck or an irregular string of 1099 payments — turning that into a plan is the next step.
FAQ
Is a 1099 job always worse for take-home pay than a W-2 job?
No — it depends on the rate, business expenses, and which benefits the W-2 job includes. As a rough 2026 example, a $70,000 contract takes home about $2,400 less than a $70,000 salary before benefits, and the gap widens once health coverage and retirement matching are priced in.
Can I just decide to be paid as a 1099 contractor instead of a W-2 employee?
No. The IRS says classification depends on the facts of the working relationship — chiefly who controls how the work is done — not on preference or what a contract says.
Do 1099 workers pay double the Social Security and Medicare tax?
Effectively yes: self-employment tax is 15.3% on 92.35% of net profit, versus 7.65% withheld from a W-2 paycheck, per IRS Topic 554. Half of it is deductible when figuring income tax, which softens the difference.
Do all 1099 workers need to make quarterly estimated tax payments?
The IRS generally requires estimated payments from people who expect to owe $1,000 or more when they file. Some people with a W-2 job instead raise their paycheck withholding to cover it.
Can 1099 workers deduct business expenses that W-2 employees can't?
Yes. Self-employed workers can deduct ordinary and necessary business expenses, while most W-2 employees can't deduct unreimbursed job costs on their federal return.
Related reading
Why is my paycheck so much smaller than my salary?
Your salary is a yearly number; your paycheck is what's left after taxes and benefits come out of each pay period. Here's a line-by-line walk from gross pay to net pay, so nothing on your stub is a mystery.
Pre-tax vs post-tax payroll deductions: what's the difference?
A $200 pre-tax deduction doesn't cost you $200 of take-home pay — but it doesn't disappear from the IRS's radar forever either. Here's how each bucket actually works.
How to budget on an irregular or variable income
Freelancers, commission earners, and gig workers can still budget with confidence. The key is budgeting off your lowest month, not your average.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.