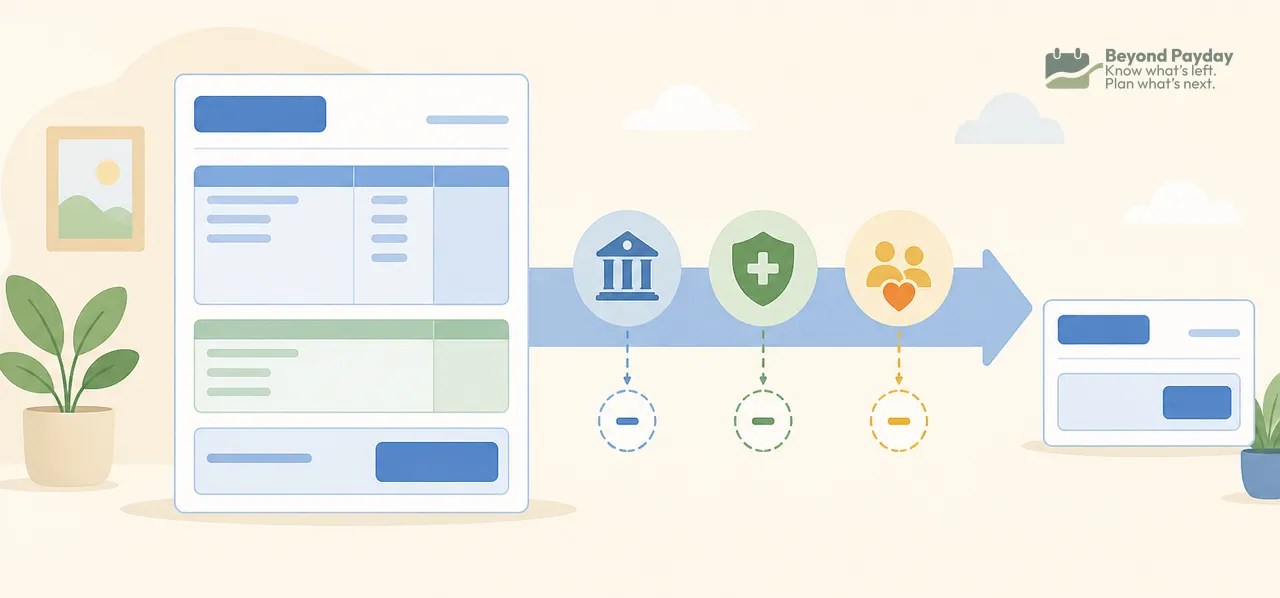
Your salary is what your employer agreed to pay you for the year. Your paycheck is what actually lands in your bank account each pay period, after taxes and benefits are subtracted. The gap between the two is entirely made up of withholding and deductions — and once you see each line, the math stops feeling mysterious.
- Gross pay minus taxes minus deductions equals net pay — every stub follows this same basic subtraction.
- Federal, Social Security, and Medicare taxes are withheld from nearly every paycheck; state and local taxes depend on where you live and work.
- Pre-tax deductions (retirement, health premiums, HSA/FSA) come out before taxes are calculated, which lowers your taxable wages.
- Post-tax deductions (Roth contributions, some insurance, garnishments) come out after taxes, so they don't reduce what you're taxed on.
- Two people with the same salary can take home very different amounts based on W-4 elections, benefits, state, and filing status.
Gross pay vs. net pay: the two numbers on every stub
Every pay stub is built around two anchor numbers.
- Gross pay — this is the number tied to your salary or hourly rate.
- Net pay — this is what shows up in your bank account.
One quick check before the line items: per-check gross depends on pay frequency. Paid biweekly, a salary is split 26 ways; semimonthly, 24. A $65,000 salary is $2,500 per biweekly check but about $2,708 per semimonthly check — same year, different stub.
Everything else on the stub is a line item that gets subtracted somewhere between those two numbers. Once you can sort each line into "tax" or "deduction," and "pre-tax" or "post-tax," the whole document makes sense.
Federal income tax withholding: who gets it and why the amount varies
Federal income tax withholding is money your employer holds back and sends to the IRS on your behalf, as a prepayment toward your annual tax bill (IRS: tax withholding).
- Withholding exists so income tax gets paid gradually across the year instead of in one lump sum.
- Form W-4 controls the amount withheld — two people with identical salaries can have very different withholding if their W-4 answers differ (IRS: tax withholding).
- The U.S. income tax system uses a graduated bracket structure, so a raise that pushes part of your income into a new bracket doesn't raise the tax rate on money you already earned (IRS: federal income tax rates and brackets).
- Rates and bracket thresholds are adjusted periodically and can change from year to year, which is one reason withholding amounts can shift even when your salary and W-4 stay the same (IRS: federal income tax rates and brackets).
Note
Withholding is an estimate, not your final tax bill. If too much or too little was withheld across the year, that gets reconciled when you file your tax return.
FICA: Social Security and Medicare taxes
FICA is the second big bite out of almost every paycheck, and unlike income tax, it isn't affected by your W-4.
- FICA covers two separate taxes that show up as their own lines (IRS: understanding employment taxes).
- Social Security tax (OASDI) is withheld at a statutory rate of 6.2% of wages, matched by an equal amount your employer pays on your behalf (IRS: understanding employment taxes).
- Medicare tax is withheld at 1.45% of wages, also matched by your employer (IRS: understanding employment taxes).
- Social Security tax only applies up to an annual earnings cap known as the contribution and benefit base, which the Social Security Administration updates annually ($184,500 in 2026) — so higher earners may notice their Social Security withholding stop partway through the year, and start again in January (SSA: contribution and benefit base).
- Once your wages at a job pass $200,000 in a year, the employer also withholds an extra 0.9% Additional Medicare Tax (IRS Topic 560).
Tip
Unlike a traditional 401(k) contribution, FICA taxes are calculated before that contribution is subtracted. Retirement contributions lower your income tax bill, not your Social Security or Medicare tax.
State and local taxes
Not every paycheck has a state or local tax line — it depends entirely on where you live and work.
- State income tax rules, rates, and even whether the tax exists at all vary by state.
- Local income tax applies in some cities and counties on top of state and federal tax.
- State-mandated insurance lines show up in some states — for example, disability or paid family leave programs in California, New York, New Jersey, Washington, and Massachusetts are funded partly through employee payroll deductions.
- Some states use their own graduated brackets, some use a single flat rate, and some don't collect a state income tax at all — which is a major reason two people with the same salary in different states can see very different take-home pay.
Pre-tax deductions: money that comes out before taxes are calculated
Pre-tax deductions lower the wages your taxes are calculated on, which is why they can shrink your tax withholding along with your paycheck.
- Pre-tax deduction reduces your taxable income for the deductions that qualify.
- 401(k) contributions (traditional version) reduce wages subject to federal and state income tax, but not FICA wages.
- Health, dental, and vision insurance premiums run through many employer plans as pre-tax deductions, lowering income tax and often FICA wages too, when offered through a qualifying benefits arrangement.
- Commuter transit and parking benefits can also come out pre-tax, up to $340 a month each in 2026 (IRS).
- HSA and FSA contributions made through payroll are typically pre-tax as well.
- These benefits are usually run through a cafeteria plan, which is why premiums and HSA/FSA contributions often reduce FICA wages in addition to income tax wages.
Post-tax deductions: money that comes out after taxes
Post-tax deductions don't lower your taxable wages at all — they're subtracted from what's left after taxes are already calculated.
- Post-tax deduction is why some benefits shrink your paycheck without touching your tax bill.
- Roth contribution to a Roth 401(k) or similar plan is a common post-tax line.
- Disability insurance premiums are often deducted post-tax on purpose: if you pay the premium with after-tax dollars, any benefit you later collect is generally tax-free.
- Garnishment is a post-tax deduction that an employer is legally required to withhold once ordered — it isn't optional and doesn't reflect a choice you made on your W-4.
Watch out
If a stub suddenly shows an unfamiliar deduction, don't assume it's a mistake — it's worth confirming with HR or payroll whether it's a new benefit election, a garnishment order, or an actual error before disputing it.
Why two people with the same salary take home different amounts
Same salary, different paycheck — this happens more often than people expect, and it's rarely a payroll error.
| Factor | How it changes take-home pay |
|---|---|
| Form W-4 elections | Filing status, dependents, and extra withholding change federal (and sometimes state) tax withheld |
| State of residence/work | Some states have no income tax; others have flat or graduated rates |
| Benefit elections | More pre-tax retirement or health contributions lower taxable wages and net pay |
| Retirement account type | Traditional contributions are pre-tax; Roth contributions are post-tax |
| Garnishments | Court-ordered deductions apply to some employees and not others |
| Coverage tier | Employee-only vs. family health coverage can differ by hundreds of dollars a month |
| Local taxes | Some cities and counties — New York City, Philadelphia, and many Ohio cities, for example — levy their own income tax |
Why the first paycheck of the year can look different
A smaller or larger January paycheck, even with no salary change, is common for a few structural reasons.
- Benefit elections often reset during open enrollment, so health premiums, HSA, or FSA contribution amounts can change starting with the first paycheck of the new plan year.
- Retirement plan contribution elections and IRS limits are set annually, and some plans automatically adjust ongoing contribution percentages or dollar amounts in January.
- Payroll systems update withholding tables for the new tax year, which can shift federal withholding slightly even without a W-4 change (IRS: tax withholding).
- The Social Security wage base resets every January, so higher earners who stopped having Social Security tax withheld late in the prior year will see it start being withheld again (SSA: contribution and benefit base).
The most common reasons a stub surprises someone
- Confusing gross pay with net pay when comparing an offer letter salary to an actual deposit.
- Forgetting FICA isn't reduced by 401(k) contributions, so Social Security and Medicare tax can look "too high" relative to taxable wages shown elsewhere on the stub.
- A new benefit election (HSA, FSA, extra life insurance) quietly starting or changing after open enrollment.
- A bonus check — treated as supplemental pay — withheld at a flat 22% federal rate (37% on amounts over $1 million), per IRS Publication 15 (2026) — often higher than the rate on your regular check. It's withholding, not the final tax; the difference settles on your return.
- Imputed income — a line that adds to taxable wages without adding cash. The classic example is employer-paid group life insurance above $50,000 of coverage, whose cost is taxable (IRS Publication 15-B).
- A garnishment order taking effect without much advance notice to the employee, since employers are generally required to comply once notified.
- Moving, or working in a new state, which can add or remove a state or local tax line entirely.
An example with real numbers: from gross pay to net pay
Illustrative numbers. Actual withholding depends on current IRS and state tables, your W-4, and your specific benefit elections.
Assumptions: Biweekly gross pay of $2,500. Pre-tax health insurance premium of $150 and pre-tax HSA contribution of $50, both run through a cafeteria plan and reducing wages for income tax and FICA. Pre-tax traditional 401(k) contribution of $125, reducing income tax wages only (FICA still applies to it). Assumed federal withholding of $180 and state withholding of $65.25, both flat assumptions rather than a table calculation. Post-tax supplemental life insurance deduction of $15.
| Step | Calculation | Amount |
|---|---|---|
| Gross pay | — | $2,500.00 |
| Pre-tax health premium | subtracted before taxes | –$150.00 |
| Pre-tax HSA contribution | subtracted before taxes | –$50.00 |
| Wages subject to FICA | $2,500 – $150 – $50 | $2,300.00 |
| Social Security tax | 6.2% × $2,300 | –$142.60 |
| Medicare tax | 1.45% × $2,300 | –$33.35 |
| Pre-tax 401(k) contribution | subtracted before income tax only | –$125.00 |
| Wages subject to income tax | $2,300 – $125 | $2,175.00 |
| Federal income tax withheld | flat assumption | –$180.00 |
| State income tax withheld | flat assumption | –$65.25 |
| Post-tax life insurance | subtracted after taxes | –$15.00 |
| Net pay | Gross minus all lines above | $1,738.80 |
Here, roughly 30% of gross pay went to taxes and deductions combined — a mix of taxes that fund government programs, savings the employee chose, and benefits that protect against future costs. The share varies widely with income, state, filing status, and benefit choices.
Once you know exactly where each dollar of your paycheck goes, it's a lot easier to plan around what's actually left. If you want a clearer picture of your real take-home pay against your bills and goals, a tool that models your deductions can help you map it out.
FAQ
Why did my first paycheck of the year look different from December's?
Benefit elections, FSA contributions, and retirement plan limits commonly reset in January. Payroll systems also update withholding tables for the new year — both can shift the numbers even if your salary didn't change.
Do pre-tax 401(k) contributions lower my Social Security and Medicare tax?
No. Traditional 401(k) contributions reduce the wages used to calculate federal and state income tax, but they're still included in the wages subject to Social Security and Medicare tax under FICA (irs.gov).
Why does my coworker take home more than me even though we earn the same salary?
Differences in Form W-4 elections, filing status, state of residence, health and retirement benefit choices, and any wage garnishments can all change take-home pay even when gross salary is identical.
Can I get back money that was over-withheld from my paycheck?
Over-withheld federal and state income tax is reconciled when you file your return. FICA generally isn't refundable, with one big exception: if two or more employers together withheld more Social Security tax than the annual maximum ($11,439 in 2026), the excess is claimed as a credit on your federal return.
Is a bigger paycheck always better than a smaller one with more benefits taken out?
Not necessarily. Pre-tax deductions like retirement and HSA contributions reduce take-home pay now, but they can lower taxable income and build savings — so the comparison depends on the full picture, not just the stub total.
Related reading
Pre-tax vs post-tax payroll deductions: what's the difference?
A $200 pre-tax deduction doesn't cost you $200 of take-home pay — but it doesn't disappear from the IRS's radar forever either. Here's how each bucket actually works.
What is a 401(k) and how does it work?
A 401(k) is an employer-sponsored account that lets you save for retirement straight from your paycheck, often with free matching money — here's exactly how contributions, matches, vesting, and taxes work.
How to make a budget that actually works
A budget only works if it matches your real income, splits fixed from variable costs, and runs on autopilot. Here's the step-by-step process.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.