A budget that works starts with one number: what actually lands in your bank account, not what your offer letter says you earn. From there, it's five steps — find your real income, sort expenses into two buckets, pick a method, automate the boring parts, and check in on a schedule. Skip any one of those and the budget quietly falls apart within a few months.
- Budget off your net income (after tax, after deductions) — never your gross salary.
- Sort every expense into fixed or variable before you assign it a category.
- Pick one method (zero-based, 50/30/20, or envelope-style) and give it 60-90 days before judging it.
- Automate transfers and bill pay so the budget still runs on a bad week.
- Review weekly in five minutes, and do a fuller check once a month.
Step 1: Find your real net income
Your budget is only as accurate as the income number underneath it. Use take-home pay, not your salary.
- If you're a W-2 employee, use the amount that hits your account after taxes, health insurance, and retirement contributions — check a recent pay stub.
- If income varies (freelance, commission, tips, seasonal work), don't average a good month. Use your lowest realistic month as the baseline — see the separate guide on budgeting irregular income for the full method.
- If you're paid biweekly, remember two months a year bring three paychecks instead of two. Budget monthly using the amount you can count on every single month, and treat the extra paycheck as a bonus to assign on purpose.
Note
Include recurring deposits you actually rely on — side income, alimony, regular reimbursements — but leave out one-time windfalls like a tax refund or a gift. Those get planned separately, not folded into the baseline.
Step 2: Split every expense into fixed and variable
Before you can build categories, sort what you already spend into two buckets.
- Fixed expense — these are the backbone of your budget because they're predictable.
- Variable expense — these are where most people find room to adjust.
A third, often-missed category:
- Irregular expense — divide the annual total by 12 and set that amount aside monthly in a dedicated sinking fund rather than letting it blow up a random month.
Step 3: Pick one budgeting method
There's no single "correct" method — the best one is whichever you'll actually keep using.
| Method | How it works | Best for |
|---|---|---|
| Zero-based | Every dollar of net income is assigned a job (spend, save, or give) until the total hits zero | People who want maximum control and don't mind more setup |
| 50/30/20 | Roughly 50% needs, 30% wants, 20% savings/debt | People who want simple guardrails without tracking every category |
| Envelope / cash-style | A fixed amount is set aside per category (physically or in sub-accounts); spending stops when the envelope is empty | People who overspend on cards and want a hard stop |
| Pay-yourself-first | Savings and debt payments come out automatically on payday; the rest is free to spend | People whose top priority is protecting a savings or payoff rate, not micromanaging categories |
Whichever you choose, write it down somewhere you'll actually look — a spreadsheet, an app, or paper. A budget that only exists in your head isn't a budget; it's a hope.
Step 4: Automate what you can
The parts of a budget that fail are the ones that depend on willpower every single day. Automation removes that dependency.
- Auto-transfer to savings the day after payday, before you can spend it.
- Autopay fixed bills from a dedicated account so a late fee never eats into the plan.
- Fund sinking funds automatically — a small recurring transfer for irregular expenses beats scrambling in December.
- Leave variable spending manual — groceries, dining, and shopping are exactly where you still want to make active choices.
Tip
A simple structure that works for a lot of people: one account for bills, one for everyday spending, and one (or more) for savings goals. Money moves automatically between them on payday, so each account only ever holds what it's meant for.
Step 5: Set a review cadence
A budget is a living document, not a form you fill out once.
- Weekly (5 minutes): glance at variable spending so far — are you on track or already over?
- Monthly (20-30 minutes): compare actual spending to the plan, category by category. Adjust categories that were consistently wrong in either direction.
- After any change: a raise, a new bill, a move, a baby, a rate hike on a loan — rebuild the numbers immediately rather than letting the old plan run on autopilot.
Common mistakes and where budgets actually break
Watch out
Most abandoned budgets fail for one of these reasons, not because "budgeting doesn't work":
- Budgeting off gross pay — leaves 15-30% less real money than the plan assumes.
- Forgetting irregular expenses — insurance, gifts, and annual fees show up as "surprise" overspending every single time.
- Being too restrictive on day one — a plan with zero fun money rarely survives more than a few weeks.
- Never updating after a raise or a new bill — an outdated budget produces numbers nobody trusts, so people stop looking at it.
- Tracking every penny by hand forever — sustainable systems automate the fixed and irregular pieces so manual effort only goes toward variable spending.
An example with real numbers
Here's an illustrative walkthrough — not a recommendation, just one way the steps come together.
Someone with $4,200 in monthly net income sorts their expenses:
- Fixed: rent $1,450, car payment $310, insurance $140, phone $60, subscriptions $35 → $1,995
- Irregular (monthly set-aside): car registration, gifts, annual memberships averaged out → $150
- Savings/debt payment (automated on payday): $500
- Remaining for variable spending: $4,200 − $1,995 − $150 − $500 = $1,555 for groceries, gas, dining, and everything else that month
They set up autopay for the fixed bills, an automatic transfer for the $150 sinking fund and $500 savings the day after each paycheck, and leave the remaining $1,555 in a spending account they check weekly. At month's end, they compare what actually happened in the variable categories to the $1,555 target and adjust next month's plan slightly if needed.
FAQ
How much of my income should go to a budget category like housing?
Common guidance suggests keeping housing near 25-35% of net income, but high cost-of-living areas often run higher. Treat any percentage as a starting reference, not a rule.
Should I budget with gross or net income?
Most budgeting approaches use net income (what actually lands in your bank account) since that's the money you can really spend, save, or move.
What if my spending never matches my budget?
A mismatch for the first month or two is normal. Track actual spending for 30-60 days, then rebuild the budget around real numbers instead of guesses.
Do I need a special app to budget?
No. A spreadsheet, a notebook, or a banking app's built-in categories can all work. The method matters less than consistency.
How often should I update my budget?
Most people benefit from a quick weekly check-in and a fuller review once a month, with a bigger recalibration after any income or expense change.
Sources and context
These primary publications explain the data and concepts identified below. Survey results and historical examples describe their stated populations and periods; they do not predict an individual outcome.
- CFPB: creating and maintaining a budget
Tracking income, spending, and bill dates to build a realistic budget.
- CFPB: Your Money, Your Goals toolkit
Income and spending trackers, cash-flow budgeting, and prioritizing bills when money is short.
Related reading
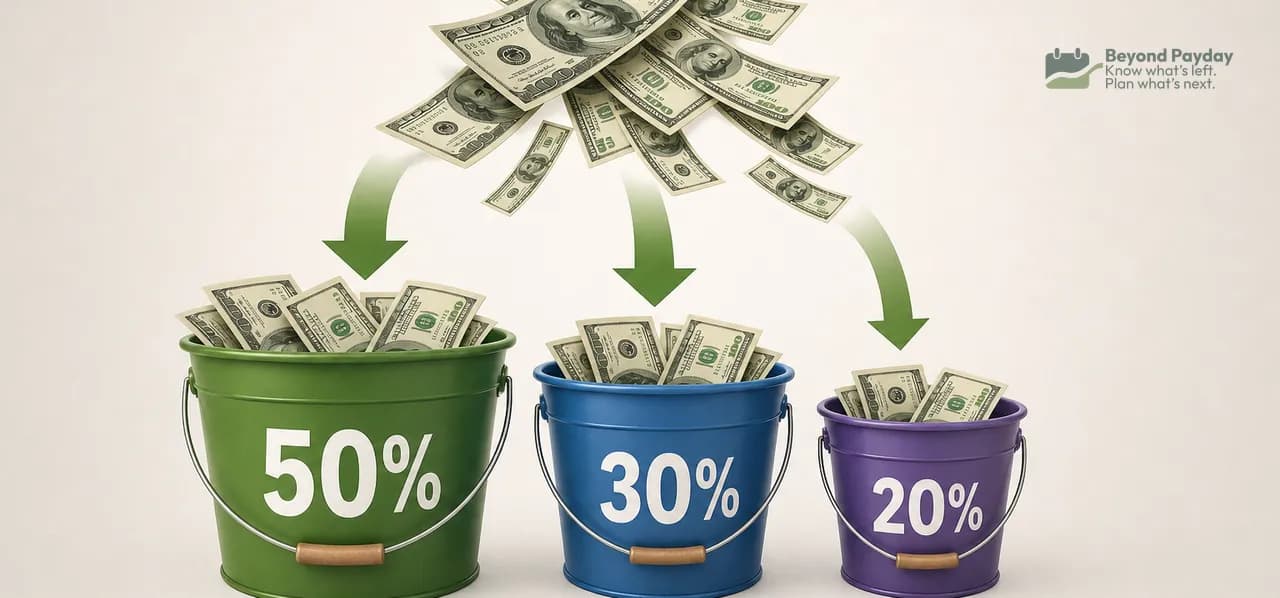
The 50/30/20 budget rule, explained
The 50/30/20 rule splits your take-home pay into needs, wants, and savings. Here's exactly how the math works, a full example, and where the rule breaks down.
Where does your money go? How to track your spending
You can't fix a budget you can't see. Here's how to track spending manually or automatically, sort it into categories that mean something, and actually use the review.
How to stop living paycheck to paycheck
Getting out of the paycheck-to-paycheck cycle usually comes down to a small cash buffer, trimming the largest expenses, and a handful of automated habits.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.