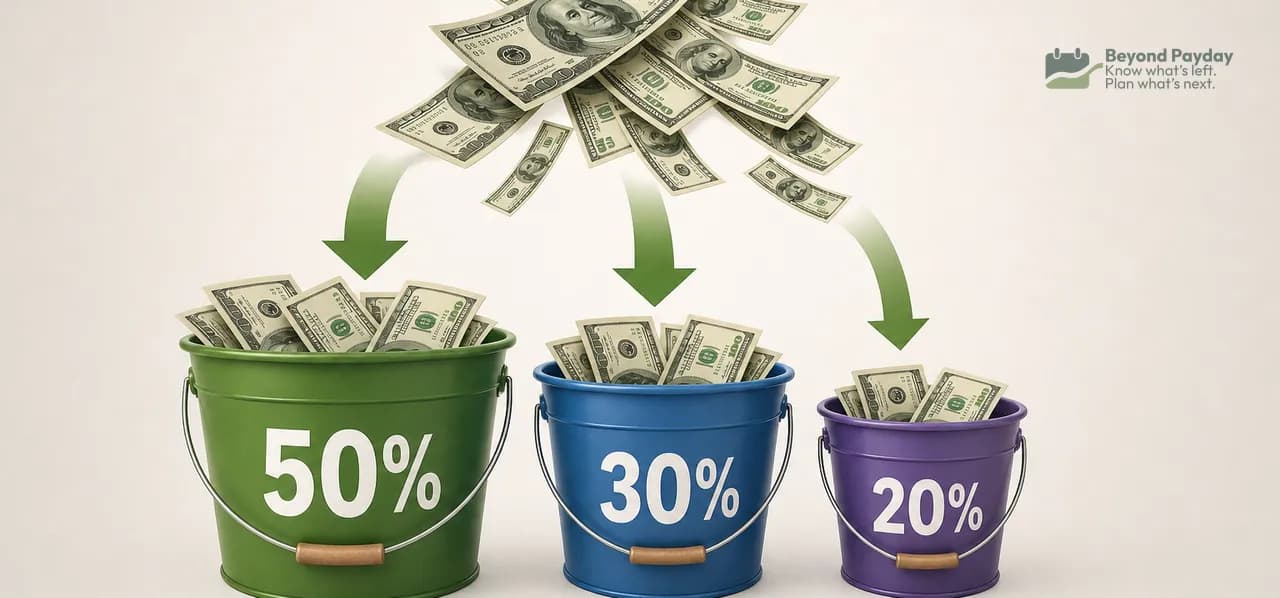
The 50/30/20 rule splits your take-home pay into three buckets: roughly 50% on needs, 30% on wants, and 20% on savings and debt payoff. It's a starting reference for how to divide money, not a strict formula — and it works better for some incomes and cities than others.
- 50% needs, 30% wants, 20% savings/debt — applied to net (take-home) income, not gross salary.
- Needs are costs you can't easily avoid; wants are costs you're choosing.
- The 20% bucket covers both building savings and paying down debt beyond the minimum.
- In high cost-of-living areas or on a lower income, needs routinely exceed 50% — the rule bends or breaks, and that's expected.
- Use it as a diagnostic starting point, then adjust the percentages to your real life.
Where the rule comes from
The 50/30/20 framework was popularized as a simple way to divide income without tracking dozens of categories. Instead of budgeting line-by-line, you sort spending into three groups and check the totals against three percentages.
The three buckets, defined
Needs (~50%)
- Need — the bills that don't disappear if you decide to cut back.
- Typical items: rent or mortgage, utilities, groceries (basic), minimum loan payments, health insurance, transportation, childcare required for work.
Wants (~30%)
- Want — the spending you're actively choosing.
- Typical items: restaurants, streaming and subscriptions, travel, hobbies, upgraded/premium versions of needs, shopping beyond necessities.
Savings & debt payoff (~20%)
- Building an emergency fund, contributing to retirement accounts, investing, and paying extra (beyond the minimum) toward debt all count here.
- Minimum debt payments go under needs; only the extra you throw at debt counts toward the 20%.
Note
Some items genuinely depend on the household. A car might be a need for a commute or a want if it's an upgrade from a paid-off car that still runs. Judge each expense by whether cutting it would meaningfully disrupt your life, not by the category label alone.
An example with real numbers
Here's an illustrative example using $5,000 in monthly net income — not a recommendation, just the math laid out.
| Bucket | Target % | Target $ | Example items |
|---|---|---|---|
| Needs | 50% | $2,500 | Rent $1,600, utilities $180, groceries $400, minimum debt payment $220, insurance $100 |
| Wants | 30% | $1,500 | Dining $350, subscriptions $60, shopping $400, travel fund $300, hobbies $390 |
| Savings/debt | 20% | $1,000 | $500 to retirement, $300 emergency fund, $200 extra toward debt |
If actual needs came to $2,600 instead of $2,500, the extra $100 has to come from somewhere — usually the wants bucket, since savings is the number most people are trying to protect.
Where 50/30/20 breaks down
Watch out
The rule assumes needs can realistically fit in half your income. That assumption fails in some common situations:
- High cost-of-living areas — rent alone can consume 40-50%+ of net income, leaving little room for a 30% wants bucket.
- Lower incomes — when total income is small, needs (housing, food, transportation) often take a larger share no matter how tightly wants are cut, since some costs have a floor.
- High debt loads — someone with significant minimum payments may find needs plus minimums already exceeds 50-60% before any wants spending happens.
- Single-income households with dependents — childcare and healthcare can push needs well past half of take-home pay.
When needs run over 50%, common adjustments include:
- Shifting to a needs-heavier split (e.g., 60/20/20 or 65/15/20) rather than abandoning percentage-based budgeting entirely.
- Treating the 20% savings target as a floor to protect, even if it means squeezing wants closer to 10-15%.
- Revisiting needs themselves — a lower rent, a cheaper car, or refinancing debt — since percentage tricks can't fix a needs bucket that's structurally too large for the income.
Nuances worth knowing
- It's a household-level rule. Splitting needs/wants/savings by category is easier than tracking every transaction, but it still requires labeling each expense honestly — it's easy to reclassify a want as a need to make the math work.
- The 20% isn't just "savings account" money. Retirement contributions, investing, and extra debt payoff all count, so someone maxing out a 401(k) match plus paying extra on a student loan may already be well past 20% without a traditional savings account balance to show for it.
- It doesn't account for irregular expenses. Annual insurance premiums, holiday spending, and car maintenance don't fit neatly into a monthly needs/wants split unless they're averaged out in advance.
- It's a starting framework, not a diagnosis of a "good" or "bad" budget. A 45/35/20 split isn't a failure if it reflects real, sustainable choices for that household.
FAQ
Is 50/30/20 based on gross or net income?
It's designed around net income — what you take home after taxes — since that's the money actually available to allocate.
Is a subscription a need or a want?
Most guidance treats subscriptions as wants unless they're required for work or a documented medical/accessibility need, since they're usually optional and cancellable.
What if my needs are more than 50% of my income?
That's common in high cost-of-living areas or on a lower income. The rule is a reference point, not a requirement — many people run a needs-heavier split instead.
Does debt payoff count as savings in the 20%?
Most versions of the rule group minimum debt payments under needs and count extra debt payoff, along with actual saving and investing, toward the 20%.
Is 50/30/20 good for someone with irregular income?
It's harder to apply directly since the percentages assume a stable paycheck. A common adjustment is applying the percentages to a conservative baseline income instead of an average.
Sources and context
These primary publications explain the data and concepts identified below. Survey results and historical examples describe their stated populations and periods; they do not predict an individual outcome.
- CFPB: a spending rule worksheet
The 50% needs, 30% wants, and 20% savings/debt guideline, with room to adapt it to individual circumstances.
- CFPB: creating and maintaining a budget
Tracking income, spending, and bill dates to build a realistic budget.
Related reading
How to make a budget that actually works
A budget only works if it matches your real income, splits fixed from variable costs, and runs on autopilot. Here's the step-by-step process.
How to stop living paycheck to paycheck
Getting out of the paycheck-to-paycheck cycle usually comes down to a small cash buffer, trimming the largest expenses, and a handful of automated habits.
How big should your emergency fund be?
The standard rule is 3–6 months of essential expenses, but the right number depends on how stable your income and job actually are.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.