Linking your bank account to a budgeting app is generally as safe as the specific connection method and the app's data practices behind it — there's no single yes-or-no answer that applies to every app. Some connections never let an app see your bank password at all; others store more than people realize. The safety question really comes down to how the link works and who holds your data once it's made.
- Bank linking usually runs through a data aggregator that sits between your bank and the app — it's rarely a direct connection.
- The safest common method is token-based (OAuth) access, where the app never sees your actual bank password.
- Older or less secure setups use credential-based access or screen scraping, which can involve the aggregator storing your login details.
- Linking saves time by importing transactions automatically, but it also means more parties are holding a copy of your financial data.
- Manual and import-based budgeting avoid live bank connections entirely but come with more data entry and no automatic updates.
- The federal open banking rule is on hold: finalized in 2024, blocked by a court in 2025, and being rewritten by the CFPB in 2026.
How bank linking actually works
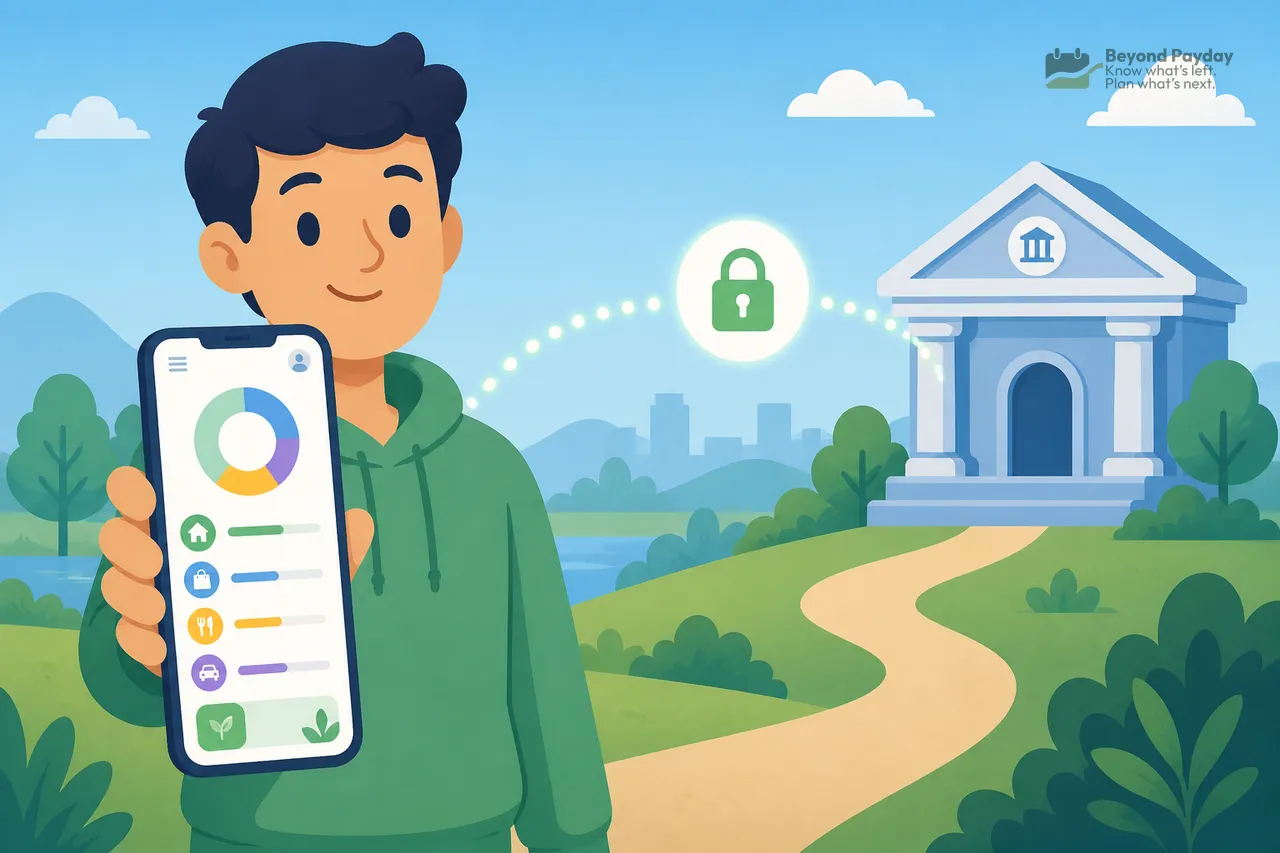
When a budgeting app asks you to "connect your bank," it's almost never talking directly to your bank's servers.
- A data aggregator sits in the middle. A data aggregator handles the technical work of connecting your bank to the app. A small number of large aggregators power the bank connections behind most budgeting apps.
- The app itself usually doesn't build the bank connection. It licenses that infrastructure from an aggregator instead of writing its own.
- The method of access matters more than the aggregator's name. The same aggregator can offer more than one connection type, and the type used affects what data the app and aggregator can see or store.
The three ways access typically works
- Token-based (OAuth) access — OAuth You type your credentials only into your bank's own login screen. The app and aggregator receive a token that grants limited access, which your bank can revoke at any time.
- Credential-based access — credential-based access Your login details pass through, and sometimes are stored by, the aggregator or app rather than staying only with your bank.
- Screen scraping — the usual engine behind credential-based access. screen scraping This was common before banks offered more secure connection options and still exists in some older integrations.
Many banks and aggregators have moved toward token-based access over time because it avoids passing around a stored password. But not every app or every bank connection uses it, which is one reason it's worth knowing which type you're agreeing to.
What data typically flows, and for how long
A linked connection usually shares more than just your balance.
- Common data shared: account balances, transaction history, account and routing numbers, account names, and sometimes account holder details.
- Your "account number" may be a stand-in. On many token-based connections to large banks, the app receives a tokenized account number rather than the real one — so a leak from that app is easier to contain.
- Access is usually ongoing, not one-time. Once connected, the app can typically keep pulling updates automatically until the connection is removed or expires.
- Duration varies by app and bank. Some connections stay active indefinitely until manually revoked; others require periodic re-authentication, especially with token-based access that a bank can time out or refresh.
- You generally can't control the frequency of pulls. How often the app refreshes your data is usually set by the app, not by you.
Note
What specifically gets shared and stored is described in each app's privacy policy and terms of service — these vary a lot between apps, so the details for any single app come from reading its own policy rather than assuming a standard.
The real benefits of linking
The appeal of linking is mostly about effort, not just convenience for its own sake.
- Transactions import automatically, so you're not manually typing every purchase.
- Balances stay current without logging into multiple bank sites separately.
- Categorization happens automatically in many apps, which can save time even if it needs occasional correction.
- It's easier to see your full financial picture across multiple accounts in one place, which supports approaches like a cash flow budget that rely on seeing all transactions together.
The real trade-offs of linking
Convenience comes with more parties holding a copy of your financial life.
- More companies have your data. Your bank, the aggregator, and the app itself may all store some version of your transaction history.
- Connections can break. Banks sometimes update their security or systems in ways that disconnect existing links, requiring you to reconnect and re-authenticate.
- Data sharing terms live in privacy policies you may not read closely. What an app does with your data — whether it's used for other purposes, shared with partners, or retained after you stop using the app — is described there, and policies differ app to app.
- A breach anywhere in the chain is exposure. If the app, the aggregator, or even the bank's own systems are compromised, whatever data was stored in that link is at risk, and the specific data exposed depends on what that link stored in the first place.
Watch out
Before linking any account, it's reasonable to check what type of connection the app uses and what its privacy policy says about data retention and sharing — that information is usually easy to find but easy to skip.
Open banking rules: written, then paused
The federal rule meant to set ground rules for this data flow exists on paper but isn't being enforced.
- What it is. The CFPB's Section 1033 rule, finalized in October 2024, required banks to share data through secure interfaces instead of screen scraping, limited apps to using data for the service you asked for, capped access at one year without reauthorization, and made revoking access end it immediately (CFPB, 2024).
- Where it stands. A federal court in Kentucky blocked the CFPB from enforcing it in October 2025 while the agency reconsiders it. The CFPB sent a revised proposal for White House review in August 2026, so the final shape — including whether banks can charge fees for data access — is still open.
- What that means today. The protections people most often assume exist come mainly from each bank's, aggregator's, and app's own policies. The CFPB's personal financial data rights page tracks the rule's status.
How to reduce risk if you do link an account
Linking doesn't have to mean handing over blind trust.
- Check the connection type where you can. Some apps disclose whether they use OAuth/token-based access versus credential-based access during setup.
- Review connected apps through your bank, not just the budgeting app. Most banks have a settings page — often called "connected apps," "data sharing," or "third-party access" — where you can see and revoke what's linked.
- Check the aggregator's side too. Some aggregators run their own consumer portal listing every app connected through them, which can surface links you've forgotten.
- Read the data section of the app's privacy policy, specifically what it says about sharing with third parties, data retention after you stop using it, and whether data is used to build other products.
- Remove access for apps you no longer use. An old, forgotten connection is still a live data pipeline until it's revoked.
- Unique passwords and multi-factor login on the bank account matter regardless of linking, and most of all in the credential-based and screen-scraping models.
- Count AI assistants as another app. Some AI chatbots now offer bank linking through the same aggregators, so the same questions — connection type, what's stored, how to revoke — apply to them.
The manual and import-based alternative
Not linking at all is a real, common choice — it just moves the work somewhere else.
- Manual entry means typing transactions in yourself, often into a spreadsheet or an app built around manual tracking, similar to the approach described in the CFPB's budgeting guidance.
- Import-based tools let you download a statement file (like a CSV) from your bank and upload it into an app periodically, avoiding a live, ongoing connection while still saving some typing.
- Both avoid an always-on link to your bank, but they still store whatever data you enter or upload, so the app's own privacy practices still matter.
Linked vs. manual budgeting: side by side
| Linked (aggregator-connected) | Manual or import-based | |
|---|---|---|
| Setup effort | Lower — connect once, data flows automatically | Higher — you enter or upload data yourself |
| Ongoing effort | Lower — updates happen automatically | Higher — requires regular entry or uploads |
| Data held by third parties | Bank, aggregator, and app may all store data | The app you use (and its hosting providers) stores what you enter |
| Live credential exposure | Depends on connection type (token vs. credential-based) | None — no live bank login involved |
| Risk if connection breaks | Requires reconnecting/re-authenticating | Not applicable — no connection to break |
| Best fit for | People who want a real-time, low-effort view of spending | People who prefer minimal data sharing or don't mind manual tracking |
Neither column is universally "the safe one." A well-secured, token-based linked connection with a transparent privacy policy can be a reasonable choice for one person. A manual spreadsheet stored only on their own device might feel better to someone else. The right fit depends on how much manual effort you're willing to trade for automation, and how comfortable you are with the specific data practices of the tools you choose.
An example
Say someone connects three accounts to a budgeting app using token-based access, then moves to a different app a year later without disconnecting the first one. The abandoned app's connection can keep pulling fresh transactions from accounts that are still open until it's revoked, the token expires, or the bank ends it. That's why checking connected-app lists periodically, not just at setup, is part of managing this kind of access.
Whichever way you go, it helps to know what you're agreeing to before you tap "connect." If you're weighing the trade-offs, it's worth taking a look at how the app you're considering describes its own data handling and connection type before deciding.
FAQ
What is a financial data aggregator, and is it safe to use?
A data aggregator is a company that builds the technical connection between a bank and an app so account information can be shared automatically. How safe a given connection is depends mostly on the access method it uses and what the app's privacy policy says it does with your data.
Can a budgeting app see my bank password?
It depends on the connection type. With token-based (OAuth) connections, you enter your login only on your bank's own site, so the app never sees it; with older credential-based methods, the aggregator may store your login to sign in on your behalf.
How do I revoke a budgeting app's access to my bank account?
Most banks list connected third-party apps somewhere in their online or mobile security settings, often under a name like 'connected apps,' 'data sharing,' or 'account access,' where you can remove a connection directly.
Are manual budgeting apps more private than linked ones?
Manual and import-based apps generally involve fewer parties handling your live bank credentials or an ongoing data feed, but they still store whatever financial data you choose to enter or upload, so privacy depends on that app's own data practices too.
What happens if a budgeting app I've linked has a data breach?
Exposure depends on what the app and its aggregator store — this can range from account balances and transaction history to, in some older setups, stored login credentials, which is why reviewing what a given connection stores matters.
Related reading
Where does your money go? How to track your spending
You can't fix a budget you can't see. Here's how to track spending manually or automatically, sort it into categories that mean something, and actually use the review.
Budget vs. cash flow: why a balanced budget can still bounce
A budget that adds up perfectly for the month can still leave you short on the 14th. Here's why budgets and cash flow answer two different questions — and how to check both.
How to make a budget that actually works
A budget only works if it matches your real income, splits fixed from variable costs, and runs on autopilot. Here's the step-by-step process.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.