A sinking fund is money you set aside each month for an expense you know is coming, but that doesn't happen every month — a car registration, a holiday season, a home repair. Unlike an emergency fund, there's no surprise involved. You know the bill is coming; a sinking fund just spreads the cost out so it doesn't land as one lump-sum shock.
It's the piece that sits between your regular monthly budget and your emergency fund, and it's the piece most budgets are missing.
- A sinking fund covers known, irregular costs — expenses you can predict but that don't fit a monthly budget line.
- It's different from an emergency fund, which exists for costs you can't predict at all.
- Most sinking-fund expenses show up if you review a full year of past spending, not just last month's.
- The basic math is simple: cost ÷ months until it's due = monthly set-aside. Year one usually costs more than later years — that's the catch-up, not a mistake.
- You can track sinking funds in one account with subcategories or in several separate accounts — each has trade-offs.
What exactly is a sinking fund
The term comes from corporate and government finance, where a borrower sets money aside on a schedule to pay down ("sink") a debt or replace an asset. In personal budgeting, it means the same idea on a smaller scale.
A sinking fund is money saved gradually, over months, for a specific expense you already know is coming — even if you don't know the exact date or amount yet.
Common examples:
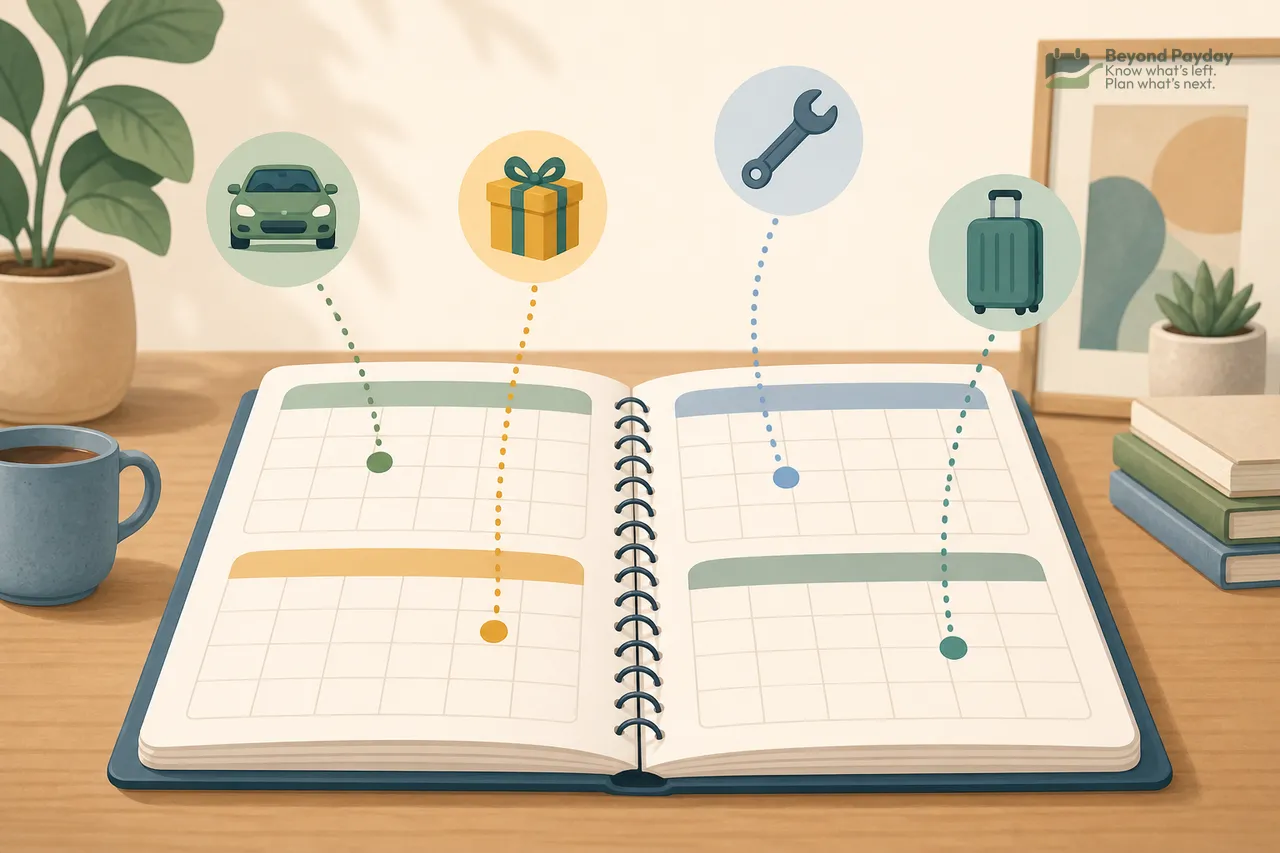
- Car registration and inspection fees — annual, predictable, easy to forget
- Holiday gifts and travel — happens every year, rarely budgeted for in January
- Insurance premiums paid annually or semi-annually instead of monthly
- Home maintenance — a roof, water heater, or appliance that won't last forever
- Back-to-school costs — supplies, clothes, fees that spike every fall
- Annual subscriptions or memberships billed once a year
None of these are emergencies. All of them are predictable enough that, with a little planning, they never have to feel like one.
Sinking fund vs. emergency fund vs. monthly budget
These three tools solve three different problems, and confusing them is one of the most common budgeting mistakes.
| Monthly budget | Sinking fund | Emergency fund | |
|---|---|---|---|
| Covers | Recurring monthly costs (rent, groceries, utilities) | Known but irregular costs (car registration, holidays) | Unpredictable costs (job loss, medical bill, major repair) |
| Timing | Predictable, monthly | Predictable, but not monthly | Unpredictable |
| Goal size | Matches monthly spending | Matches the specific expense | Depends on the household — the Consumer Financial Protection Bureau suggests sizing it from the unexpected costs you've actually faced |
| How it's built | Paycheck-to-paycheck allocation | Small deposits spread across the months before the bill is due | Built up over time, ideally kept separate and untouched until needed |
An emergency fund is meant to stay untouched until something genuinely unexpected happens. A sinking fund, by contrast, is supposed to get spent — on a known date, for a known reason — and then refilled for next time.
Why these expenses are what actually break a budget
A budget can look perfectly balanced on paper and still fall apart every few months. Sinking funds are usually the reason why.
- They don't happen every month, so they're invisible in a typical month-by-month budget review.
- They cluster — holiday spending, back-to-school costs, and year-end insurance renewals often land in the same few months.
- They feel like emergencies even though they aren't, because the household wasn't holding money aside for them.
- They get paid with credit by default, since there's no dedicated cash sitting ready when the bill arrives.
- They're easy to underestimate — a $1,200 annual premium feels abstract until the bill actually shows up.
The result: someone can do everything right on rent, groceries, and daily spending, and still feel like their budget "doesn't work" — when the real issue is a handful of predictable expenses with no home in the plan.
How to find your sinking-fund categories
The fastest way to spot them is to look backward, not forward.
- Pull twelve months of spending — bank and credit card statements, not just the current month.
- Flag anything that wasn't monthly — annual bills, one-off large purchases, seasonal spikes.
- Group similar items together — "car stuff," "gifts," "home repairs" — even if the amounts vary.
- Note the rough timing — some costs cluster in certain months (December, back-to-school season, renewal months for insurance).
- Add anything foreseeable but not yet in the data — a car that's aging toward needing tires, a planned trip.
Anything that shows up once or twice a year, isn't optional, and wasn't already covered by the emergency fund is a sinking-fund candidate.
Tip
If a cost repeated in the past two or three years around the same time of year, it's very likely to repeat again — that's usually a strong sign it belongs in a sinking fund rather than being treated as a one-time surprise.
Working out the monthly amount
The basic formula is simple:
Annual (or known) cost ÷ number of months until it's due = monthly set-aside amount
A few adjustments make it more accurate:
- Use the actual due date, not just "per year." If a $600 insurance premium is due in 4 months, that's $150/month, not $50/month.
- Round up slightly for costs that tend to rise over time, like home repairs or insurance renewals.
- Re-estimate annually once you have a full year of actual data instead of a guess.
- Split large, lumpy costs (like a major home repair) across a longer runway if the timing is flexible.
- Watch for pay-in-full pricing. Many insurers charge installment fees for monthly billing or discount paying the full term upfront. A funded sinking fund is what makes the cheaper option possible.
Common sinking-fund categories
The categories below are common starting points.
| Category | Typical frequency | Example annual cost* | Example monthly set-aside |
|---|---|---|---|
| Car registration/inspection | Annual | $150 | $12.50 |
| Holiday gifts & travel | Annual (Nov–Dec) | $1,200 | $100 |
| Insurance premiums (paid annually) | Annual or semi-annual | $900 | $75 |
| Home maintenance & repairs | Irregular, ongoing | $1,500 | $125 |
| Back-to-school costs | Annual (Aug–Sept) | $600 | $50 |
| Annual subscriptions/memberships | Annual | $300 | $25 |
| Car maintenance (tires, brakes) | Every 1–3 years | $800 (spread over 2 yrs) | ~$33 |
*Example figures, not averages. Actual costs depend on the household, vehicle, region, and policy.
Where to hold the money: one account vs. several
Both approaches work. The right one depends on how much structure someone needs to avoid quietly spending the money on something else.
One account, tracked by category (mentally or with a spreadsheet/app)
- Pros: Simple to set up, no extra bank accounts to manage, easy to see the total sinking-fund balance at a glance.
- Cons: Requires discipline to track subcategories accurately — it's easy to lose track of how much is "really" earmarked for holidays versus car repairs, and easy to accidentally dip into it for unrelated spending.
Multiple accounts, one per category
- Pros: Each fund is visually separated, which can make it harder to accidentally spend gift money on car repairs, and easier to see progress toward each specific goal.
- Cons: More accounts to open and monitor, and moving money between institutions can add friction and, depending on the bank, occasional fees or minimum balance rules.
Note
Neither method is objectively better — the goal is simply that the money for a specific known expense is identifiable and not accidentally spent on something else before it's needed.
Where it sits matters more than what it earns. Because each fund has a due date, most people keep it in an FDIC- or NCUA-insured savings account rather than in investments that could drop right before the bill arrives.
Common mistakes
Watch out
The most common mistake is treating a predictable annual bill as a fresh "emergency" every single time it arrives — which quietly drains an actual emergency fund meant for genuine surprises.
- Skipping the review step and guessing at categories instead of checking actual past spending.
- Underestimating cost creep — insurance premiums and home repair costs often rise year over year.
- Merging sinking funds with the emergency fund, which makes it hard to know how much is truly available for a real emergency.
- Not adjusting after the bill hits — if the actual cost came in different from the estimate, next cycle's monthly amount needs to change with it.
- Trying to fund every category at once when the budget is tight, instead of prioritizing the largest or soonest expenses first.
An example with real numbers
Assumptions:
- Car registration: $150/year, due in 6 months → $150 ÷ 6 = $25/month
- Holiday spending: $1,000/year, due in 10 months (starting in March) → $1,000 ÷ 10 = $100/month
- Annual insurance premium: $840/year, due in 12 months → $840 ÷ 12 = $70/month
- Home maintenance: $1,200/year target, ongoing → $1,200 ÷ 12 = $100/month
Total monthly sinking-fund contribution: $25 + $100 + $70 + $100 = $295/month
Limitations: it assumes costs don't change during the saving period, and it ignores whether $295/month fits the household's income and other priorities.
Notice that $295 × 12 = $3,540, but the four costs only add up to $3,190 a year. That gap is the catch-up effect: bills due soon (like the registration in 6 months) need bigger deposits the first time around. Once every fund is running on its normal 12-month cycle, the steady-state amount drops to about $3,190 ÷ 12 ≈ $266/month.
Tip
Starting late makes year one feel expensive. That's a one-time catch-up, not the real long-run cost of the plan.
Getting started
Once the categories and monthly amounts are worked out, the harder part is usually just remembering to move the money consistently and keeping track of which balance belongs to which goal — especially once there are four or five categories running at once.
FAQ
Is a sinking fund the same as an emergency fund?
No — a sinking fund is for expenses you can predict, like an annual insurance premium, while an emergency fund is for costs you can't predict, like a job loss or an urgent repair.
Do I need a separate bank account for every sinking fund category?
Not necessarily — one account with tracked subcategories works for many people, while separate accounts can add friction that discourages spending the money on something else.
What if I can't afford to fund every category right away?
Many people start with one or two of the largest or most frequent expected costs and add categories as their budget allows, rather than trying to fund everything at once.
How is a sinking fund different from just budgeting more carefully each month?
A regular monthly budget usually covers costs that repeat every month; a sinking fund spreads out costs that hit only once or a few times a year so they don't appear as one large surprise expense.
Should sinking fund money earn interest?
Some people keep sinking fund money in an interest-bearing account since it's not needed immediately, though the priority is usually accessibility over yield since spending dates are often fixed.
Related reading
How big should your emergency fund be?
The standard rule is 3–6 months of essential expenses, but the right number depends on how stable your income and job actually are.
How to make a budget that actually works
A budget only works if it matches your real income, splits fixed from variable costs, and runs on autopilot. Here's the step-by-step process.
Where does your money go? How to track your spending
You can't fix a budget you can't see. Here's how to track spending manually or automatically, sort it into categories that mean something, and actually use the review.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.