A recession budget is a plan for what your household would cut, keep, and prioritize if income dropped — built while things are still calm, so you're working from a checklist instead of a panic. It usually has tiers: your normal budget, a trimmed version, a bare-bones version, and an emergency version for if income stops almost entirely.
You don't need a recession to be officially declared to build one. The value is in having the decisions already made.
- A bare-bones budget covers only what's needed to keep the household running — housing, utilities, food, insurance, minimum debt payments, transportation to work.
- Runway = current savings ÷ the monthly gap (bare-bones cost minus any income that would keep coming). It tells you roughly how many months essentials stay covered.
- Stress-testing means running the numbers for a realistic income drop — a layoff, reduced hours, or lost commission — before it happens, not during.
- Some moves are easier before a downturn: reviewing insurance, understanding unemployment eligibility in general terms, lowering fixed costs, and avoiding new long-term commitments.
- The most common mistakes are cutting so hard the plan can't be kept, panic-selling investments, cancelling insurance to save money, and pulling from retirement accounts without understanding the penalties and taxes involved.
Step 1: Sort every expense into essential vs. cuttable
Start with a full list of what the household spends money on each month. For each line, ask: does this need to keep running if income stopped tomorrow?
Usually essential:
- Housing (rent or mortgage payment)
- Utilities (electricity, water, heat, basic phone/internet)
- Groceries and basic household supplies
- Insurance premiums (health, auto, home/renters)
- Minimum payments on existing debt
- Transportation needed to get to work or job search
- Childcare needed to keep working
Usually cuttable, in order of how painful it feels to cut:
- Subscriptions and streaming services
- Dining out and takeout
- Discretionary shopping and entertainment
- Gym memberships, upgraded phone/internet tiers
- Travel and vacations
- Extra debt payments beyond the minimum
- New retirement or investment contributions (beyond any employer match, which is a separate decision)
This is also where discretionary spending earns its name — it's the spending that flexes first. The CFPB's budgeting guidance (2019) suggests starting small — reviewing expenses a week at a time or keeping a daily log — before deciding what to trim, since small recurring costs are easy to underestimate.
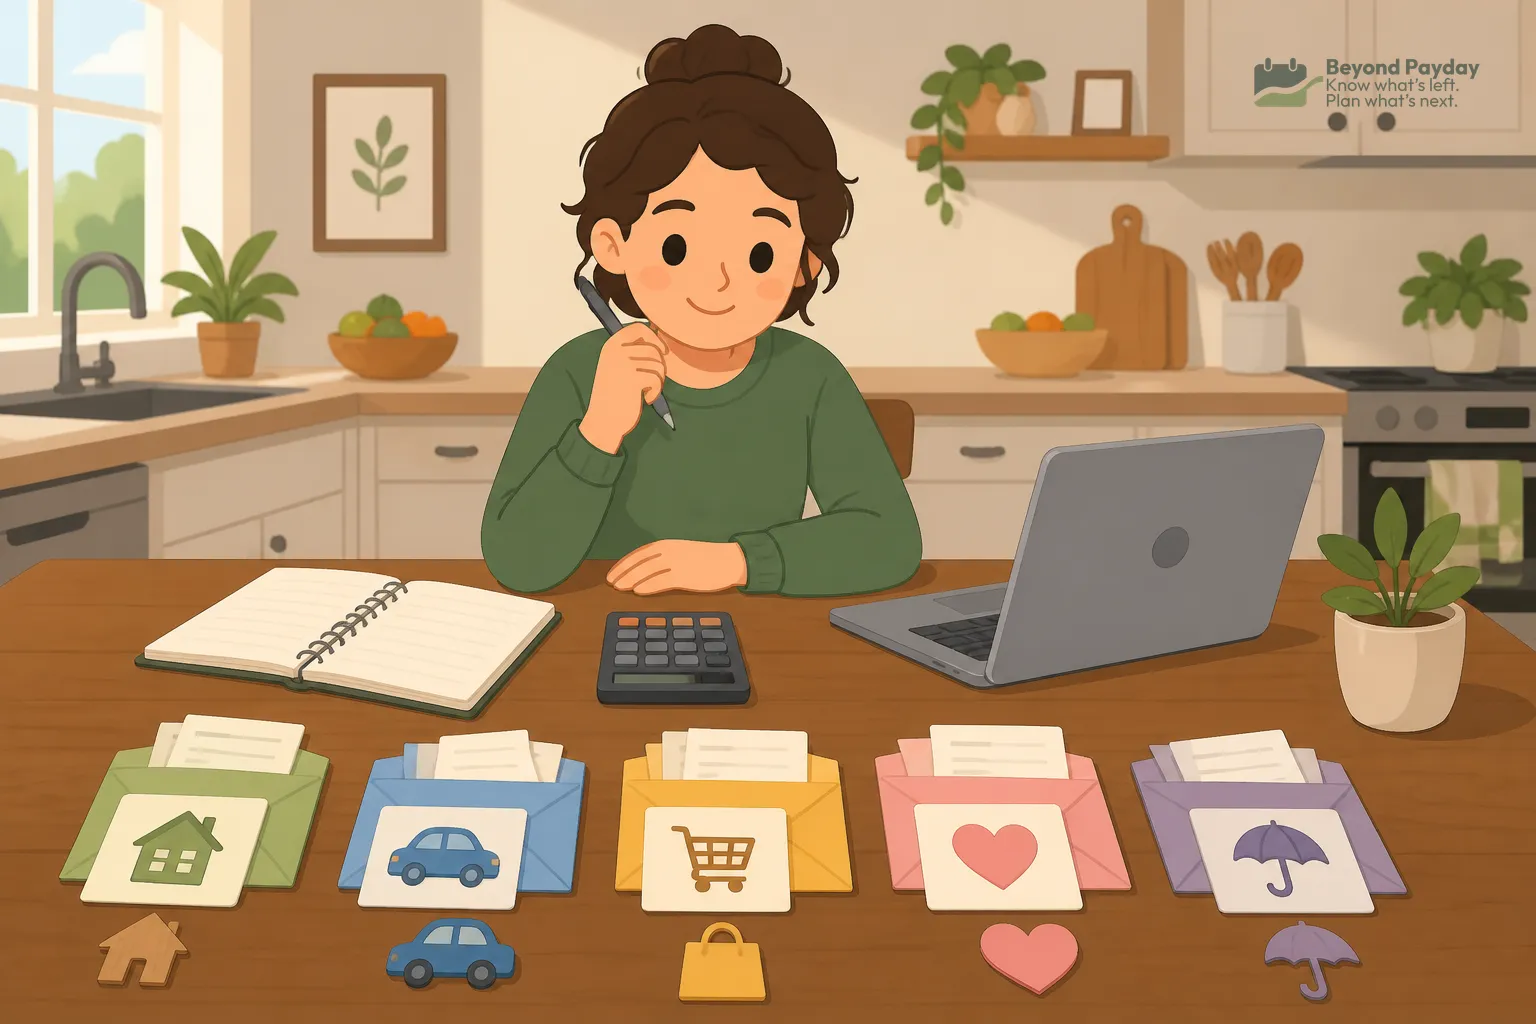
Step 2: Build your bare-bones monthly number
A bare-bones budget is the sum of everything on the essential list above, and nothing else.
Write it as one number: the minimum it would cost this household to keep the lights on, the rent or mortgage paid, insurance in force, and debt current — for one month.
This number does two jobs:
- It's the target for how much cash the household would need to hold to weather a gap in income.
- It's the plan that gets activated if income actually drops, instead of scrambling to figure out what to cut in real time.
Step 3: Measure your runway
Emergency fund runway turns a savings balance into a timeframe — which is usually more useful than the dollar amount by itself.
Illustrative example:
- Savings set aside for emergencies: $9,000
- Bare-bones monthly cost calculated in Step 2: $3,000
- Runway = $9,000 ÷ $3,000 = 3 months
- Same household, but $1,200 a month in unemployment benefits or a partner's pay keeps coming in: the gap is $1,800, so runway = $9,000 ÷ $1,800 = 5 months
Counting income that would keep coming is what turns a scary number into an honest one — but only count money that's reliable. This is a simplified example with rounded numbers to show the formula, not a target every household should hit. Actual runway needs vary by job stability, number of earners, industry, and how quickly a household could realistically replace income.
Stress-test the household for a real income drop
A runway number is only useful if it's tested against something realistic. A few scenarios worth running on paper:
- One earner is laid off. Recalculate the household budget using only the remaining income(s). Does the bare-bones number still get covered, or does it need savings to fill the gap — and if so, for how long?
- Hours get cut, not eliminated. A partial income drop (fewer hours, reduced overtime) is common in a slowdown and often gets overlooked because it feels less dramatic than a full layoff — but the math still needs to work.
- Commission or variable pay drops. For sales, gig, or tip-based income, a slower season can cut take-home pay significantly even with the same hours worked. Modeling a lower-than-usual month shows whether fixed costs still fit.
- Both partners' income dips at once. Less common, but worth a quick check for households where both incomes are tied to the same industry or region.
Running these scenarios isn't about predicting doom — it's closer to a fire drill. The goal is knowing where the plan holds and where it doesn't, while there's time to adjust calmly.
What people commonly prioritize when money gets tight
When income actually drops, most households aim to protect the same handful of things first:
- Keeping housing current — rent or mortgage payments, since falling behind here has the most serious consequences.
- Keeping utilities on — heat, electricity, water.
- Keeping insurance in force — health, auto, and home/renters coverage, since a gap in coverage can turn a bad month into a financial emergency.
- Staying current on minimum debt payments — to avoid late fees, penalty interest rates, and damage to credit.
- Building or preserving cash — pausing extra debt payments or discretionary savings temporarily in favor of holding liquid cash during the uncertainty.
The order can shift by household — someone with no debt and a paid-off car has different pressure points than someone with a car loan and high-interest credit card debt. The point of the tiered plan below is deciding the order in advance.
Decisions that are easier before a downturn than during one
Some moves take time, paperwork, or a clear head — all of which are in shorter supply during an actual income drop. Doing them early is lower-stress and often produces better outcomes:
- Reviewing insurance coverage and shopping rates. Comparing policies takes time and a clear head, not something to start after a claim is urgent.
- Understanding unemployment eligibility in general terms. Each state runs its own unemployment insurance program with its own rules for eligibility, waiting periods, and benefit calculation — knowing generally how the process works (and where to apply) before it's needed removes one unknown during a stressful week. Two details people often miss: regular benefits last up to 26 weeks in most states and fewer in some, per the U.S. Department of Labor, and they replace only part of prior wages. They're also taxable income at the federal level, per the IRS.
- Knowing the health-insurance fallback. Losing job-based coverage opens a 60-day window to enroll in a Marketplace plan (HealthCare.gov). COBRA keeps the same plan, but often at a much higher cost than the employee share people are used to. Comparing both ahead of time avoids a rushed decision.
- Lowering fixed costs where possible. Refinancing, renegotiating a rate, or downsizing a recurring bill is easier to research without the pressure of an active income gap.
- Avoiding new fixed commitments. Signing a longer lease, financing a new vehicle, or adding a new subscription tier is a bigger risk to take on right before or during uncertain conditions than in a stable stretch.
The tiered plan: decide the cuts before you need them
A tiered budget lets a household pick, in advance, exactly what changes at each level — so a real income drop just means moving down a row, not starting from scratch.
| Category | Normal | Trimmed | Bare-bones | Emergency |
|---|---|---|---|---|
| Housing | Full payment | Full payment | Full payment | Full payment (top priority); ask the lender or landlord about hardship options early |
| Utilities & insurance | Full service | Full service | Full service, shop for lower rates | Full service, request hardship options if needed |
| Groceries | Regular shopping | Reduce brand-name/extras | Basic staples only | Basic staples only |
| Transportation | Normal use | Reduce discretionary driving | Essential trips only | Essential trips only |
| Debt payments | Minimum + extra | Minimum + occasional extra | Minimum only | Minimum only; contact lenders if at risk |
| Subscriptions & entertainment | Full | Cancel unused ones | Cancel all | Cancel all |
| Dining out / discretionary shopping | Regular | Reduced | Paused | Paused |
| Savings & extra investing | Regular contributions | Reduced contributions | Paused (except employer match, case by case) | Paused; focus on cash preservation |
A household can decide now which row applies at which income level — for example, "if take-home pay drops more than 20%, move to Trimmed; if one earner loses their job entirely, move to Bare-bones." Having those triggers defined ahead of time removes a lot of the guesswork later.
Tip
Writing the tiers down — even in a simple note or spreadsheet — makes them easier to actually follow later. A plan that only exists as a vague intention is much easier to skip under stress.
Common mistakes to watch for
Watch out
- Panic-selling investments after a market drop turns a paper loss into a real one and risks missing any rebound — a decision that's hard to undo once made.
- Cancelling insurance to save money removes protection right when unexpected costs (medical, auto, property) become more likely to actually hurt.
- Pulling from retirement accounts early without understanding the cost can turn a short-term cash need into a long-term setback. Withdrawals before age 59½ are generally taxed as income and can carry an extra 10% tax, with some exceptions (IRS). Separately, an outstanding 401(k) loan can come due in full after leaving a job. A tax professional or plan administrator can explain the rules that apply.
- Cutting so hard the plan can't be kept. A bare-bones budget that's too extreme to sustain for more than a week often gets abandoned entirely — a slightly less severe plan that actually gets followed is usually more useful than a perfect one that doesn't.
A simple starting point
A recession budget isn't a prediction that something bad is coming — it's closer to a fire extinguisher. Most months, it just sits there. Having it means the response to a job loss, a pay cut, or a slow season is "open the plan," not "figure this out from scratch while stressed."
Building the tiers, the bare-bones number, and the runway calculation once — and revisiting them occasionally as income or expenses change — is the core of preparing without needing to feel alarmed about it.
If sketching out those tiers on paper or in a spreadsheet sounds like a hassle, a tool that works from your real bills and savings can show how long the runway lasts and what to cut first.
FAQ
How much should I have in a bare-bones emergency fund?
There's no single number that fits everyone. A common rule of thumb is three to six months of bare-bones expenses, with more often suggested for single-income households, variable pay, or less stable industries.
Is a recession budget different from a regular monthly budget?
A recession budget is usually a stripped-down version of a regular budget, built in advance so a household knows exactly which costs would stay and which would pause if income fell.
Should I stop contributing to retirement accounts during a recession?
That's a personal decision that depends on job security, existing savings, and employer matching, and is worth discussing with a financial or tax professional rather than deciding based on headlines alone.
How do I know if a recession is actually coming?
Economists watch hiring, spending, and output, but US recessions are officially dated by the National Bureau of Economic Research, often many months after they begin — the recession that started in December 2007 wasn't declared until December 2008. That's why many people focus on being ready rather than trying to time one.
What's the difference between trimming a budget and going bare-bones?
A trimmed budget cuts extras while keeping some comfort spending; a bare-bones budget cuts everything down to costs needed to keep the household running, such as housing, utilities, food, insurance, and minimum debt payments.
Related reading
How big should your emergency fund be?
The standard rule is 3–6 months of essential expenses, but the right number depends on how stable your income and job actually are.
How to stop living paycheck to paycheck
Getting out of the paycheck-to-paycheck cycle usually comes down to a small cash buffer, trimming the largest expenses, and a handful of automated habits.
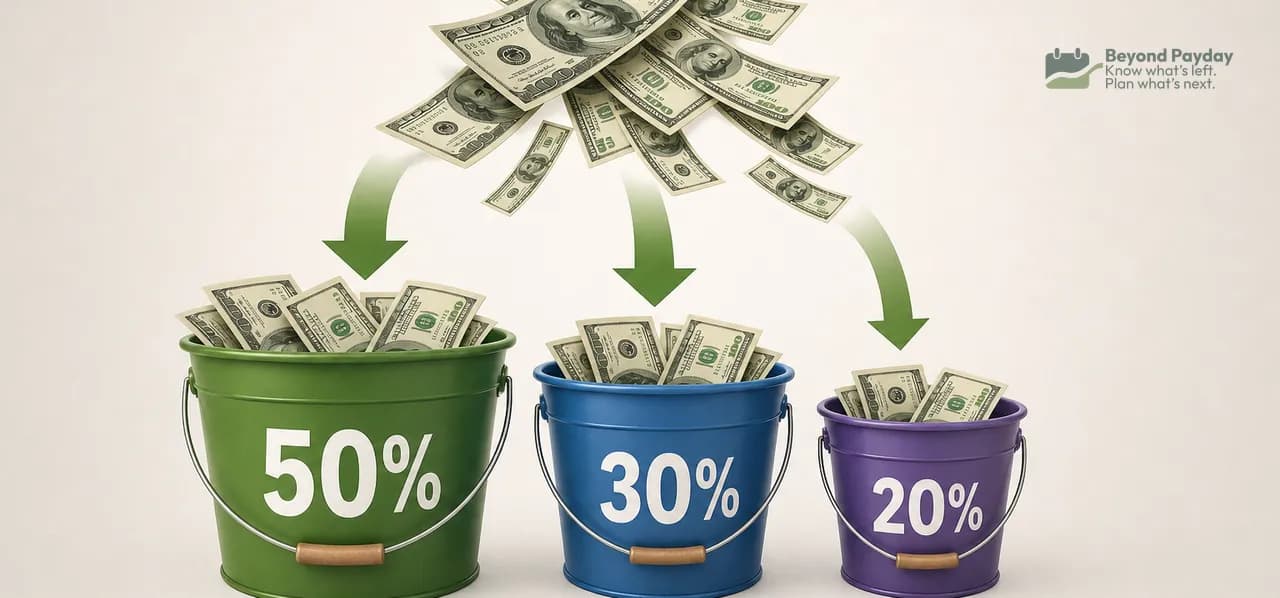
The 50/30/20 budget rule, explained
The 50/30/20 rule splits your take-home pay into needs, wants, and savings. Here's exactly how the math works, a full example, and where the rule breaks down.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.