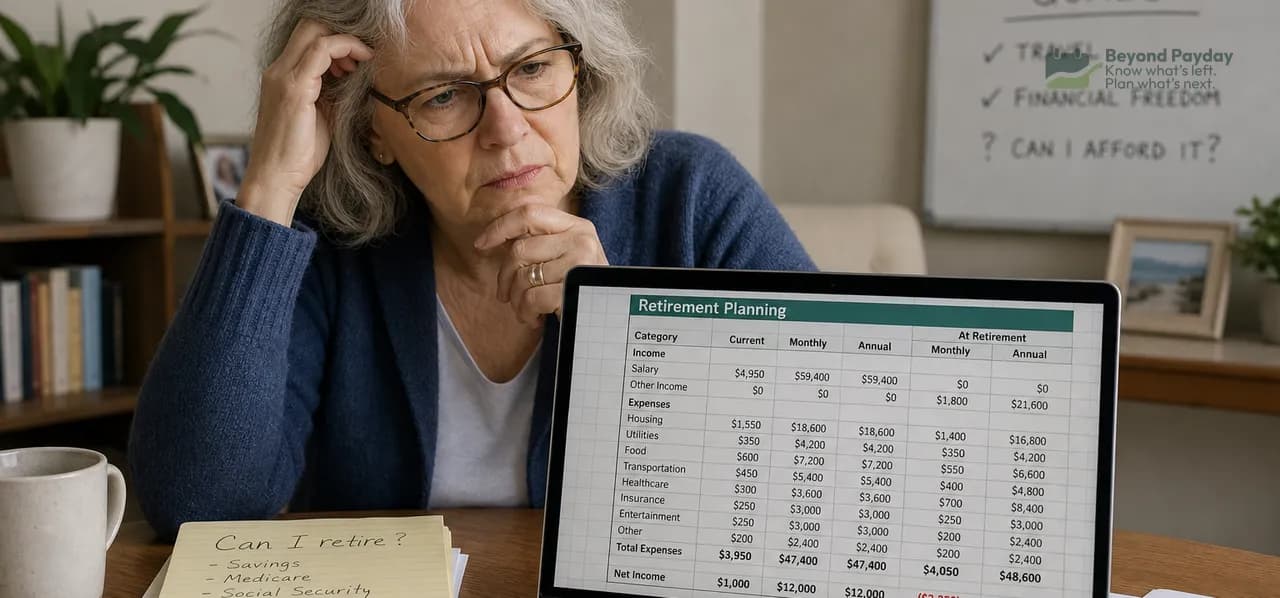
Most rules of thumb land in the same neighborhood: you need enough invested savings that a modest, sustainable withdrawal rate covers the gap between what you'll spend and what guaranteed income already covers. For a lot of households that works out to somewhere between 10 and 25 times their annual expenses, and the exact multiple depends heavily on Social Security, pensions, and how long retirement needs to last.
- The 25x rule: multiply the annual expenses you'll need to fund yourself (after subtracting Social Security/pensions) by 25.
- It's built on the 4% rule — a starting withdrawal rate that historically survived 30+ year retirements in most market conditions.
- The replacement-rate method targets 70-85% of your pre-retirement income instead, and can produce a different number than the expense-based approach.
- Guaranteed income (Social Security, a pension) shrinks the pile you need to self-fund — the more of your expenses it covers, the smaller your target.
- No formula is precise. Health, housing status, and longevity swing the real number substantially, so treat any output as a range, not a deadline.
The 25x rule, step by step
The takeaway: figure out what you'll actually need your savings to cover, then multiply by 25.
- Estimate annual retirement expenses. Start from your current spending and adjust — commuting costs usually drop, healthcare usually rises, travel or hobbies may increase.
- Subtract guaranteed income. Look up your estimated Social Security benefit and any pension income.
- Multiply the remaining gap by 25. That gap is what your invested savings need to produce each year.
For example, someone expecting $60,000 in annual expenses with $24,000 in Social Security needs their portfolio to supply $36,000 a year — a target of roughly $900,000 (36,000 x 25).
Note
25x is just the inverse of a 4% withdrawal rate (1 divided by 0.04 = 25). The two rules of thumb are really the same idea expressed two ways.
Where the 4% comes from
The takeaway: 4% is a historically tested starting point, not a guarantee.
The idea traces back to research (often called the Trinity study) that tested different starting withdrawal percentages against decades of historical U.S. market returns. The finding: a portfolio split roughly between stocks and bonds, with an initial 4% withdrawal that then rises with inflation each year, survived at least 30 years in the large majority of historical periods tested.
Key things that rule depends on:
- A 30-year time horizon. Retire earlier and you may need a lower starting rate; retire later (or have a shorter life expectancy) and a higher rate may be reasonable.
- A diversified stock/bond portfolio. An all-cash or all-bond portfolio behaves very differently.
- U.S. historical returns. Future returns are not guaranteed to match the past.
- Adjusting for inflation, not spending. The rule assumes your dollar withdrawal grows with inflation regardless of market performance, which is more rigid than how most retirees actually spend.
The replacement-rate method
The takeaway: instead of projecting future expenses, target a percentage of your current income.
Many financial planners use a shorthand: aim to replace 70-85% of your pre-retirement income through savings withdrawals plus Social Security combined. The logic is that some costs disappear in retirement (payroll taxes, retirement account contributions, sometimes a mortgage) while others may not change much.
| Method | What it uses | Best for |
|---|---|---|
| Expense-based (25x) | Your projected retirement spending | People with a clear budget or detailed retirement plan |
| Replacement-rate | A percentage of current income | Quick estimates when detailed spending isn't mapped out yet |
The two methods can disagree, sometimes significantly, especially for high earners who save a large share of their income (their expenses are much lower than their income) or low earners (a smaller share of income is typically saved, so expenses run closer to income).
The big factors that move your number
- Social Security covers a meaningful chunk of expenses for most retirees — the timing of when you claim it (age 62-70) changes the monthly benefit substantially and is one of the single biggest levers on how much you need saved.
- Pensions are less common than a generation ago but, where they exist, directly reduce the savings target the same way Social Security does.
- Healthcare costs tend to rise with age and are easy to underestimate, especially the years between an early retirement and Medicare eligibility at 65, when coverage typically must be purchased directly.
- Housing status matters enormously — a paid-off mortgage versus ongoing rent or a mortgage payment can be the single largest swing factor in annual expenses.
- Longevity — a retirement that needs to last 35-40 years (an early retiree, or simply a long lifespan) needs a larger cushion or lower withdrawal rate than one expected to last 20 years.
- Taxes — withdrawals from traditional 401(k)s and IRAs are generally taxable income, so a pre-tax balance funds less real spending than the same dollar amount in a Roth account.
Nuance, exceptions, and common mistakes
Watch out
A common mistake is assuming every household’s spending follows the same path. David Blanchett’s 2014 retirement-consumption study found that average inflation-adjusted spending generally declined with age. Its “spending smile” describes how the rate of decline varied, rather than a universal late-life rise in total spending. Healthcare can take a larger share of spending even as total real spending falls. Individual households may follow different paths.
- Treating 4% as a rule instead of a range. Some researchers now suggest 3-3.5% for retirements expected to last more than 30 years, given more conservative long-term return expectations.
- Ignoring sequence-of-returns risk — a market downturn in the first few years of retirement can do outsized damage to a portfolio that's also being drawn down, even if long-run average returns are fine.
- Forgetting one-time costs, like a new roof, a car replacement, or helping family, that don't show up in a monthly budget but happen periodically.
- Skipping inflation entirely in long-range projections — even moderate inflation compounds meaningfully over a 20-30 year retirement.
- Not revisiting the number. A target set at 45 should be revisited as actual expenses, health, and market performance become clearer closer to retirement.
An example with real numbers
This is illustrative only, not a recommendation. Consider a hypothetical household expecting:
- $70,000 in annual expenses in retirement
- $30,000 combined in estimated Social Security benefits
- A gap of $40,000 per year to be funded by savings
Using the 25x rule: $40,000 x 25 = a target of $1,000,000 in invested retirement savings. Using a more conservative 3.5% withdrawal assumption instead of 4%, the same $40,000 gap implies a larger target of roughly $1,140,000 ($40,000 / 0.035). Neither number is "correct" — they're two reasonable estimates bracketing a range, and actual results depend on real market returns, actual spending, and how long the money needs to last.
FAQ
Is $1 million enough to retire on?
It depends entirely on your spending. Under the 4% rule, $1 million supports roughly $40,000 of annual withdrawals before Social Security, which is comfortable in a low-cost area and tight in an expensive one.
What is the 4% rule exactly?
It's a guideline that withdrawing 4% of your portfolio in your first year of retirement, then adjusting that dollar amount for inflation each year after, historically lasted 30 years or more in most U.S. market periods.
Does the 25x rule include Social Security?
No. The 25x rule is usually applied to the portion of your expenses not already covered by guaranteed income like Social Security or a pension, not your total spending.
Is the 4% rule outdated?
It's debated. Some researchers argue lower expected future returns justify a more conservative 3-3.5% starting withdrawal rate, especially for retirements longer than 30 years.
How does healthcare change the number?
Healthcare before Medicare eligibility can be a large, easy-to-underestimate expense, and even after Medicare starts, premiums, supplemental coverage, and out-of-pocket costs typically rise with age.
Sources and context
These primary publications explain the data and concepts identified below. Survey results and historical examples describe their stated populations and periods; they do not predict an individual outcome.
- William Bengen: historical withdrawal-rate research
Historical stock/bond portfolio withdrawals and retirement horizons; historical survival is not a future guarantee.
- David Blanchett: retirement consumption research (2014)
Changes in inflation-adjusted retirement spending; the spending smile describes varying rates of decline, not a universal late-life spending increase.
- Social Security Administration: planning for retirement
Retirement claiming ages from 62 to 70 and how waiting affects monthly benefits.
Related reading
How much should you have saved for retirement by age?
Widely cited benchmarks suggest saving roughly 1x your salary by 30, 3x by 40, 6x by 50, and 10x by 67 — but the number that actually matters most is your savings rate, not a single checkpoint.
When can you actually retire? How to know if you're on track
Retiring isn't about hitting a birthday — it's about your savings, spending, and guaranteed income lining up so a sustainable withdrawal rate covers your life. Here's the math that actually answers the question.
What is a 401(k) and how does it work?
A 401(k) is an employer-sponsored account that lets you save for retirement straight from your paycheck, often with free matching money — here's exactly how contributions, matches, vesting, and taxes work.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.