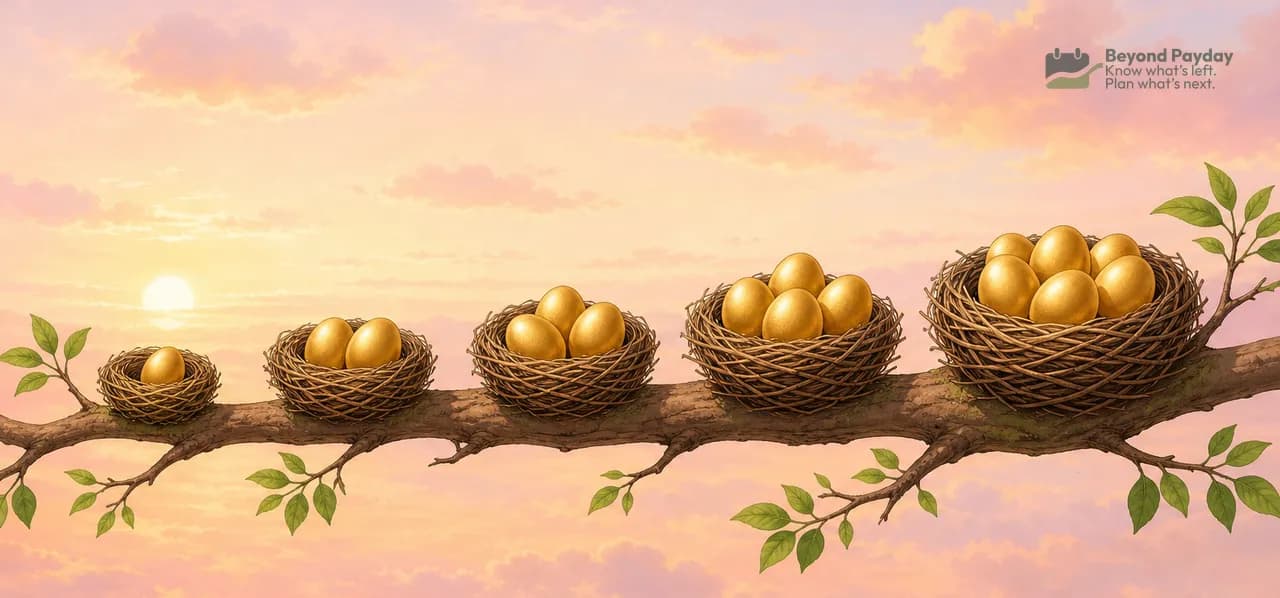
A widely cited 2026 Fidelity retirement savings analysis suggests aiming for roughly 1x your salary saved by 30, 3x by 40, 6x by 50, 8x by 60, and 10x by 67. These are useful checkpoints, not a scorecard — the savings rate that gets you from one milestone to the next matters more than where you land on any single birthday.
- Common age-based multipliers: 1x salary by 30, 3x by 40, 6x by 50, 8x by 60, 10x by 67 (assuming Social Security covers part of retirement income).
- These benchmarks assume a savings rate around 15% of income starting relatively early and invested mostly in stocks when young.
- Catch-up contributions let people 50 and older put extra money into 401(k)s and IRAs above the standard annual limit.
- Being behind a benchmark is common — what matters most from here is your savings rate and time horizon, not where you stand today.
- A savings rate is more actionable than a multiple: it tells you what to change, while a multiple only tells you where you stand.
The age-based multiplier benchmarks
The takeaway: these are checkpoints assuming steady saving from your 20s or 30s onward, not hard requirements.
| Age | Savings target (x annual salary) |
|---|---|
| 30 | 1x |
| 35 | 2x |
| 40 | 3x |
| 45 | 4x |
| 50 | 6x |
| 55 | 7x |
| 60 | 8x |
| 67 | 10x |
These figures, from Fidelity's 2026 retirement savings guidelines, come from modeling a hypothetical earner who saves consistently starting in their 20s, invests mostly in stocks early on and more conservatively over time, and plans to retire around 67 while also collecting Social Security. If your career path, income growth, or planned retirement age looks different, your own realistic multiple will too.
Note
The multiplier is applied to your current salary, not a fixed dollar figure, so the actual savings target rises automatically as your income grows.
The savings rate that gets you there
The takeaway: a savings rate in the 10-15% range (including any employer match) starting in your 20s or 30s is the most commonly cited target to reach these benchmarks by a traditional retirement age.
- Starting earlier lowers the required rate. Money saved in your 20s has decades to compound, so reaching the same milestone requires a smaller percentage of income than starting in your 40s.
- Starting later raises it. Someone beginning in their 40s often needs a meaningfully higher rate, sometimes 20% or more, to catch up to the same relative benchmark.
- Employer matching counts toward the rate, but not toward your take-home savings discipline — many benchmarks assume it's included in the 10-15% figure.
- Raises are a natural opportunity to increase your savings rate before lifestyle spending absorbs the extra income.
Catch-up contributions
The takeaway: after 50, the IRS generally allows you to contribute more per year to tax-advantaged retirement accounts.
Catch-up contribution limits are set (and periodically adjusted) by the IRS and apply on top of standard annual contribution limits for 401(k)s and IRAs. They exist specifically to help people closer to retirement make up ground, and can meaningfully accelerate progress toward a savings benchmark in your 50s and early 60s when income is often at its highest.
By-decade guidance
In your 20s and 30s
- Prioritize getting the full employer match if one is offered — it's an immediate, guaranteed return on that portion of savings.
- Favor a higher allocation to stocks given the long time horizon before withdrawals begin.
- Small increases now compound enormously by retirement age due to time in the market.
In your 40s and 50s
- This is typically peak earning years — a natural point to push savings rate higher if it slipped earlier.
- Start paying attention to catch-up contribution eligibility as 50 approaches.
- Begin thinking about a gradual shift toward more conservative investments as retirement gets closer, though the right pace depends on individual risk tolerance and time horizon.
In your 60s
- Get a clearer picture of expected Social Security timing (claiming between 62 and 70 changes the benefit significantly).
- Model healthcare costs, especially any gap between retiring and Medicare eligibility at 65.
- Revisit the withdrawal strategy — how the saved multiple will actually convert into sustainable annual income.
Nuance and common mistakes
Watch out
A common mistake is comparing your multiple to a benchmark built for a "typical" earner when your income path, career breaks, or planned retirement age look very different. Use the benchmark as a rough compass, not a report card.
- Comparing gross multiples across very different incomes. A high earner and a modest earner reaching the "same" multiple may have very different actual lifestyles funded.
- Ignoring career breaks or income volatility — the benchmarks assume smooth, continuous saving, which doesn't reflect caregiving gaps, self-employment, or job loss that many people experience.
- Panicking over being behind at one age. A single snapshot doesn't account for a raise, an inheritance, paying off debt, or years of catch-up ahead.
- Not adjusting for a non-traditional retirement age. Someone planning to retire earlier than 67 needs to reach a higher multiple sooner; someone planning to work longer has more runway.
- Forgetting non-retirement assets like home equity or a taxable brokerage account, which some people count toward overall net worth but not toward these retirement-specific benchmarks.
An example with real numbers
This is illustrative only. Consider a hypothetical 45-year-old earning $90,000 a year with $270,000 saved for retirement — that's a 3x multiple, below the commonly cited 4x benchmark for that age. Raising their savings rate from 10% to 15% of income going forward, while leaving time and compounding to work, is one illustrative way that gap could be closed by their mid-50s, though actual results depend on investment returns, income changes, and market performance that can't be predicted in advance.
FAQ
Where do the age-based savings multipliers come from?
They're commonly published by large retirement plan providers based on modeling a typical earner's income growth, savings rate, and expected Social Security, most famously in Fidelity's 2026 retirement savings guidelines.
What if I'm behind these benchmarks?
Being behind a benchmark at one age is common and not predictive on its own; what matters most going forward is your savings rate, time horizon, and any catch-up contributions you're able to make.
What are catch-up contributions?
Starting at age 50, the IRS generally allows additional contributions above the standard annual limit to 401(k)s and IRAs, letting people closer to retirement save more per year.
Is a savings rate or a savings multiple more useful?
Both are useful for different things: a multiple tells you where you stand today, while a savings rate tells you the behavior that gets you to the next milestone.
Do these benchmarks assume Social Security?
Yes, most published age-based multiples assume Social Security will cover a portion of retirement income, which is one reason they shouldn't be treated as a total, standalone target.
Sources and context
These primary publications explain the data and concepts identified below. Survey results and historical examples describe their stated populations and periods; they do not predict an individual outcome.
- Fidelity: retirement savings benchmarks and assumptions
Salary-multiple retirement savings guidelines; these are model-based benchmarks, not household net-worth statistics.
- IRS: 401(k) plans
Employee contributions and the tax treatment of traditional and designated Roth 401(k) distributions.
Related reading
How much money do you need to retire?
There's no single magic number, but a few well-tested rules of thumb — the 25x rule, the 4% rule, and the replacement-rate method — get most people surprisingly close to a real target.
When can you actually retire? How to know if you're on track
Retiring isn't about hitting a birthday — it's about your savings, spending, and guaranteed income lining up so a sustainable withdrawal rate covers your life. Here's the math that actually answers the question.
What's the average net worth by age?
Average net worth by age varies wildly depending on whether you look at the mean or the median. Here's why that gap matters and rough, survey-based figures by decade.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.