Asset allocation is how the money in a portfolio is divided among broad categories — usually stocks, bonds, and cash. That split drives most of how a portfolio behaves: how much it swings, how far it can fall, and roughly how fast it can grow. It's also a decision that tends to change as the day you need the money gets closer.
- Asset allocation is the mix of categories in a portfolio — and it shapes risk far more than any single holding does.
- A landmark 1986 study found allocation policy explained about 94% of the ups and downs in large pension funds' returns over time.
- Portfolios drift on their own as one category outgrows another; rebalancing nudges the mix back.
- The mix commonly shifts as time horizon shortens — but age-based rules of thumb disagree with each other and ignore most of what matters.
- Risk tolerance and risk capacity are different things and can pull in opposite directions.
What asset allocation actually means
Every holding sits in a broad category. The three most common:
- Stocks (equities) — ownership stakes in companies. Historically the highest long-term growth, and the deepest short-term drops.
- Bonds (fixed income) — loans to governments or companies that pay interest. Historically steadier than stocks, but not risk-free — bond prices fall when interest rates rise.
- Cash and cash equivalents — savings accounts, money market funds, and similar. Stable and easy to reach, but historically the lowest growth, often barely keeping pace with inflation.
Asset allocation is the percentage split across these. A "60/40" portfolio, for example, is 60% stocks and 40% bonds. Within each category, diversification spreads the money across many holdings.
Why the split matters more than the picks
The category weights set a portfolio's personality before a single holding is chosen.
- The classic evidence. Gary Brinson, Randolph Hood, and Gilbert Beebower's 1986 study in the Financial Analysts Journal looked at 91 large U.S. pension plans from 1974 to 1983. Allocation policy explained about 93.6% of the variation in each plan's returns over time.
- What that number does not mean. It's widely misquoted as "allocation drives 94% of your returns." A 2000 follow-up by Roger Ibbotson and Paul Kaplan, also in the Financial Analysts Journal, clarified it: allocation explained about 90% of a fund's swings over time, about 40% of the differences between funds, and roughly 100% of the average fund's return level.
- The practical takeaway. An 80%-stock portfolio will behave like a stock portfolio no matter which stocks are inside it. The mix sets the ride; the picks mostly fine-tune it.
- Picks and costs still matter. Fees, taxes, and how well each category is diversified all chip away at (or protect) returns over decades.
What rebalancing is, and why a portfolio drifts
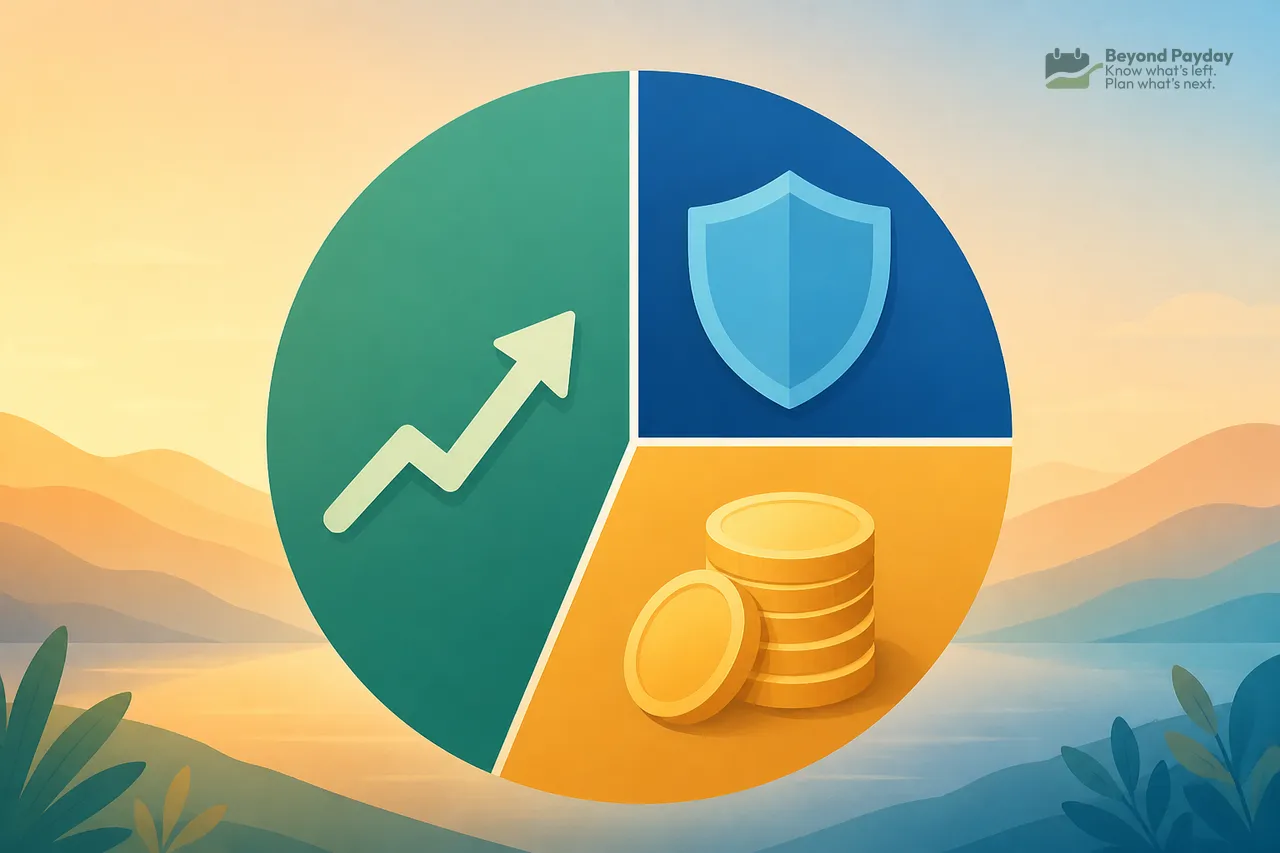
A portfolio's mix rarely stays where it started, because the categories inside it grow at different speeds.
- Drift happens automatically. If stocks outrun bonds, the stock share rises even if nothing was bought or sold. After a long bull market, a 60/40 portfolio can quietly become 75/25 — with more risk than anyone chose.
- Rebalancing resets the mix. It means trimming what grew into an oversized share and adding to what lagged.
- Two common schedules. The SEC's Investor.gov notes some experts rebalance at set intervals, such as every six or 12 months, while others rebalance when a category drifts past a preset percentage. It adds that rebalancing tends to work best when done relatively infrequently.
- Rebalancing is maintenance, not a forecast. It keeps a chosen level of risk in place. It isn't a bet on which category will do better next.
- It feels backwards. Rebalancing means selling some of what's been winning and buying what's been losing. That discomfort is exactly why many people skip it.
Tip
Where you rebalance changes the tax bill. Selling inside a 401(k) or IRA generally doesn't trigger tax. Selling in a regular taxable account can. That's why some investors rebalance inside retirement accounts first, or steer new contributions toward the category that's fallen behind instead of selling anything. Tax rules vary, so a CPA can say how they apply to you.
Why the mix commonly shifts as the goal gets closer
Time horizon — how long until the money is needed — is one of the main reasons an allocation changes.
- A long horizon leaves time to recover. Investor.gov notes that investors with a longer time horizon may feel comfortable taking on riskier, more volatile investments.
- A short horizon doesn't. As retirement, a home purchase, or tuition gets close, a big drop has less time to come back before the money is spent.
- Target-date funds automate this. A target-date fund follows a preset glide path and rebalances for you. Glide paths differ a lot between fund companies, so two funds with the same target year can hold very different mixes.
- Retirement isn't the finish line. Money for a 30-year retirement is spent over decades, so part of it still has a long horizon on the day someone retires.
Note
Time horizon is about when the money is needed, not age. A 30-year-old saving for a down payment next year and a 30-year-old saving for retirement have very different horizons.
Common age-based rules of thumb — and their limits
Several rough heuristics turn age into a stock percentage. They're widely repeated, and they don't agree with each other.
| Rule of thumb | Stock share at age 30 (example) | Stock share at age 60 (example) |
|---|---|---|
| "100 minus age" | 70% | 40% |
| "110 minus age" | 80% | 50% |
| "120 minus age" | 90% | 60% |
Calculated from the rules of thumb above.
- One input: age. None of them account for other savings, income stability, a pension, other goals, or how someone handles volatility.
- They disagree by a lot. At 60, the three versions span 40% to 60% stocks.
- They ignore guaranteed income. A retiree with a pension and Social Security covering most bills has more capacity for stock swings than one living entirely off savings — even at the same age.
Watch out
None of these rules say what any particular person's allocation should be. They're starting points with one input and well-known blind spots.
Risk tolerance vs. risk capacity
These get used interchangeably, but they measure different things.
- Risk tolerance is emotional. It's how someone feels watching the balance drop. Some shrug off a 30% paper loss; others lose sleep over 5%.
- Risk capacity is financial. It's how much loss someone can absorb without real damage — job stability, emergency savings, other income, and when the money is needed all factor in.
- They can point in opposite directions. A 62-year-old retiring next year might feel fine with big swings (high tolerance) but have little room to absorb a crash (low capacity). A nervous 28-year-old might be the reverse.
- Both matter. Tolerance decides whether someone sticks with the plan in a downturn. Capacity decides whether a downturn actually causes harm. Many planners treat the lower of the two as the real limit.
An example of drift
Setup: a $10,000 portfolio at 60% stocks / 40% bonds — $6,000 in stocks, $4,000 in bonds.
Assumption: over some period, stocks grow 30% and bonds grow 5% (illustrative numbers).
Calculation:
- Stocks: $6,000 × 1.30 = $7,800
- Bonds: $4,000 × 1.05 = $4,200
- New total: $12,000
- New stock share: $7,800 / $12,000 = 65%
- New bond share: $4,200 / $12,000 = 35%
Result: the portfolio drifted from 60/40 to 65/35 without anyone buying or selling. Getting back to 60/40 would mean moving about $600 from stocks to bonds ($12,000 × 60% = $7,200 target for stocks) — or adding new money to bonds instead.
Limitation: real markets don't move at one steady rate, and drift can just as easily run the other way after a stock decline.
FAQ
Is there one ideal asset allocation for everyone?
No. Appropriate mixes vary with an individual's goals, time horizon, income stability, and other circumstances, so there's no single allocation that fits every investor.
How often should a portfolio be rebalanced?
Approaches vary — some investors rebalance at set intervals, like every six or 12 months, per the SEC's Investor.gov; others wait until a category drifts past a set percentage. Rebalancing tends to work best when it isn't done too often.
Does a longer time horizon always mean holding more stocks?
A longer time horizon is often associated with a larger allocation to categories like stocks, per investor education materials. But this is a general tendency, not a rule that applies in every situation.
What's the difference between risk tolerance and risk capacity?
Risk tolerance is how comfortable someone feels with ups and downs in value, while risk capacity is how much financial loss someone can absorb without derailing other goals — the two don't always point the same direction.
Can two people the same age have very different allocations?
Yes. Allocation depends on individual factors like goals, other assets, income stability, and risk capacity, not age alone, so same-age investors can reasonably land on different mixes.
Related reading
Index funds vs. picking individual stocks: the trade-offs
Index funds and stock picking differ in diversification, cost, taxes, and effort — and the long-run data on who beats the market is surprisingly lopsided. Here's how each one actually works.
How compound growth actually works, in plain numbers
Compound growth means your returns start earning their own returns. Here's what that looks like over 10, 20, and 30 years — and why starting early usually matters more than starting big.
High-yield savings vs investing: where should your money go?
The choice usually comes down to time horizon and risk, not which one is "better" — here is how to think about splitting money between the two.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.