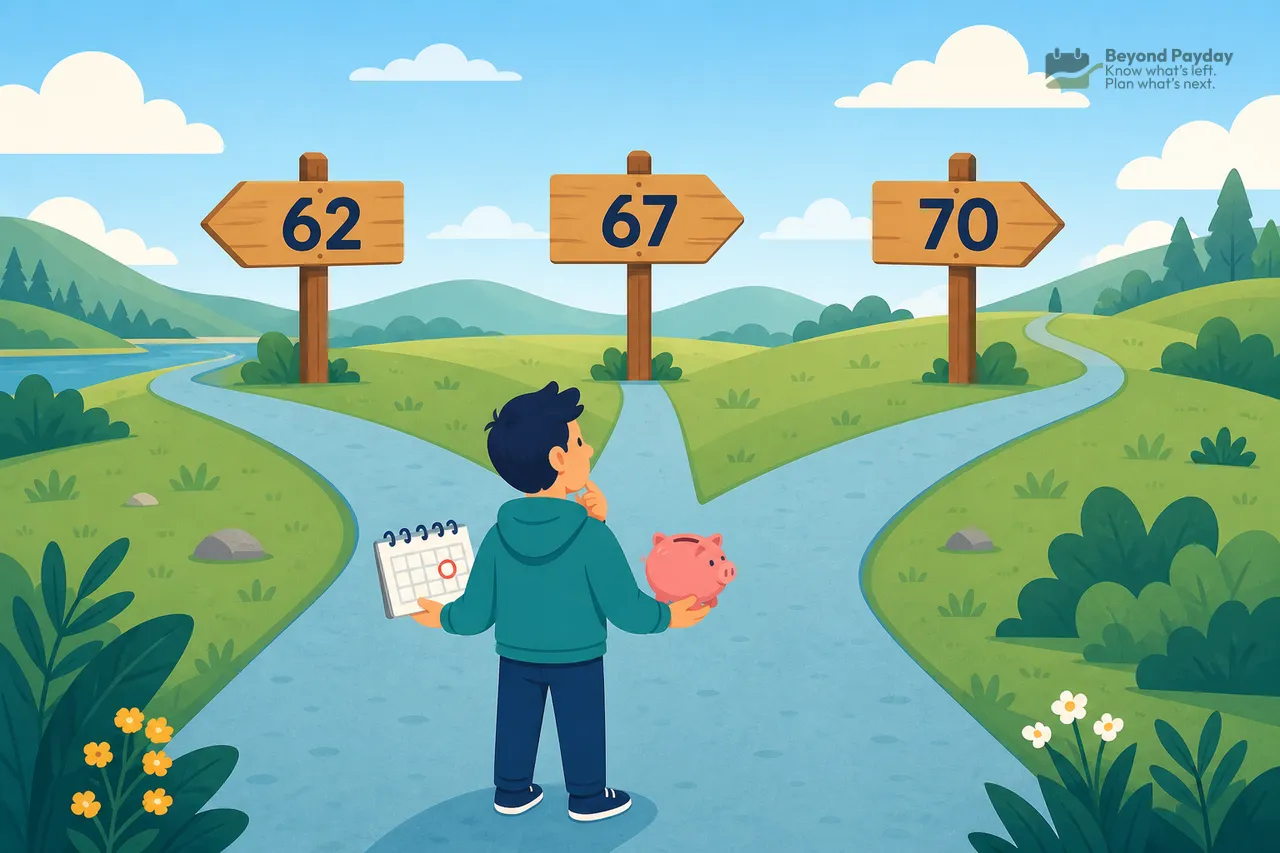
Claiming Social Security at 62 locks in a smaller monthly check for life. Waiting until 70 locks in a larger one. There's no single right age — it depends on health, other income, whether you're still working, and what a spouse might need later — but the math behind the choice follows fixed, published rules.
- Claiming before full retirement age (FRA) permanently reduces the monthly benefit; claiming after FRA, up to age 70, permanently increases it, per SSA rules. For anyone born 1960 or later, that's 70% of the full benefit at 62 and 124% at 70.
- FRA depends on birth year — it's 66 for people born 1943–1954, rising in steps to 67 for anyone born 1960 or later.
- The breakeven age — where total dollars from waiting catch up to claiming early — usually lands in the late 70s to early 80s — and it's only one factor among several.
- A spouse's survivor benefit is often tied to the higher earner's claiming age, which is why couples sometimes weigh this decision jointly.
- Your own numbers will differ — the SSA's my Social Security account shows a personalized estimate based on your actual earnings record.
What is full retirement age?
Full retirement age (FRA) isn't the same for everyone. The Social Security Administration sets it based on birth year:
| Birth year | Full retirement age |
|---|---|
| 1937 or earlier | 65 |
| 1938 | 65 and 2 months |
| 1939 | 65 and 4 months |
| 1940 | 65 and 6 months |
| 1941 | 65 and 8 months |
| 1942 | 65 and 10 months |
| 1943–1954 | 66 |
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 or later | 67 |
This table reflects how the SSA publishes full retirement age by birth year. One quirk: anyone born on January 1 uses the previous year's row.
How claiming early or late changes the benefit
Social Security benefits are built around one reference point: the amount payable at full retirement age. Move away from that age in either direction, and the math is symmetrical but not identical.
- Claiming early (as young as 62): the benefit is permanently reduced. According to SSA rules, the benefit drops 5/9 of 1% for each of the first 36 months before FRA and 5/12 of 1% for each month beyond that. At 62, that's a 30% cut for anyone with an FRA of 67 (born 1960 or later) and 25% for an FRA of 66.
- Waiting past FRA (up to age 70): the benefit grows through delayed retirement credits For people born in 1943 or later, that's 2/3 of 1% per month — 8% per year, simple, not compounded — so an FRA-67 benefit tops out at 124% at age 70, per SSA guidance.
- After age 70: there's no additional benefit to delaying further. Delayed credits stop accruing at 70, so claiming later than that doesn't increase the monthly amount.
- Both directions are permanent. Once benefits start, the reduction or increase built in at that claiming age generally stays in place for life (aside from routine annual cost-of-living adjustments that apply to everyone regardless of claiming age).
The breakeven age
Breakeven age It answers one narrow question: if I live to a given age, which claiming choice paid out more in total dollars by then?
The table below uses illustrative numbers and ignores taxes, inflation adjustments, and any investment growth on money received earlier.
Assumptions for this example:
- Full retirement age (FRA) of 67, with a benefit at FRA of $2,000/month ($24,000/year).
- Claiming at 62 reduces this to roughly $1,400/month ($16,800/year), reflecting the ~30% reduction for claiming five years early.
- Claiming at 70 increases it to roughly $2,480/month ($29,760/year), reflecting the 24% increase from delayed retirement credits (8% a year for 3 years).
- No cost-of-living adjustments are applied across the years for simplicity, and each amount is assumed to be collected starting at the stated claiming age through the comparison age shown.
| Claiming age | Monthly benefit (example) | Total by 75th birthday | Total by 80th birthday | Total by 85th birthday | Total by 90th birthday |
|---|---|---|---|---|---|
| 62 | $1,400 | $218,400 | $302,400 | $386,400 | $470,400 |
| 67 (FRA) | $2,000 | $192,000 | $312,000 | $432,000 | $552,000 |
| 70 | $2,480 | $148,800 | $297,600 | $446,400 | $595,200 |
Here, claiming at 62 produces the most cumulative income until the late 70s. Waiting to FRA overtakes claiming at 62 at about age 78 and 8 months. Waiting to 70 overtakes claiming at 62 at about 80 and 4 months, and overtakes FRA at about 82 and 6 months. The crossover points shift with different benefit amounts and cost-of-living adjustments.
Watch out
Breakeven math assumes both dollar streams are treated equally and that nothing else changes. It doesn't account for taxes, what the money is invested in, health changes, or a spouse's survivor benefit. Treating breakeven age as the only factor is one of the most common mistakes people make with this decision.
Factors people weigh beyond the math
The breakeven table only measures dollars and time. Most people weigh several other things alongside it.
Health and family longevity
- A personal or family history of longer lifespans may make later claiming look more favorable in hindsight, and vice versa — though no one can know their own lifespan in advance.
- Current health conditions, not just family history, are often part of this consideration.
Other savings and income
- Someone with a pension, retirement account withdrawals, or other steady income may have more flexibility to delay claiming without needing the money immediately.
- Someone relying on Social Security as a primary income source may weigh the need for cash flow now more heavily.
Still working and the earnings test
- Claiming before FRA while still working can trigger the earnings test
- The 2026 limits: SSA withholds $1 for every $2 earned above $24,480. In the calendar year someone reaches FRA, it's $1 for every $3 above $65,160, counting only earnings before the FRA month, per SSA. The limits rise most years.
- Money withheld under the earnings test isn't lost forever — the SSA recalculates the benefit upward at FRA to account for the months withheld, per SSA.
- This test no longer applies once someone reaches full retirement age, regardless of how much they earn.
A spouse's survivor benefit
- A surviving spouse can generally receive the higher of their own benefit or a survivor benefit based on the deceased spouse's record.
- Because of this, the higher earner's claiming age in a couple can affect what the surviving spouse receives for the rest of their life, not just what the higher earner receives while both are alive.
- Delayed credits pass to the survivor. If the higher earner waits until 70 and dies first, the surviving spouse can step up to that 124% check. That makes the higher earner's delay partly a form of life insurance for the other spouse.
- Spousal benefits don't grow past FRA. A spousal benefit tops out at 50% of the worker's full-retirement-age amount, and SSA says the worker's delayed credits don't raise it. There's no reason for the lower earner to delay a spousal benefit past their own FRA.
- Survivors can start as early as 60 (reduced), which opens options like taking the survivor benefit first and switching to one's own benefit later, or the reverse.
- Divorced spouses count too. A marriage that lasted 10 years or more can qualify an unmarried ex-spouse, 62 or older, for spousal or survivor benefits on the other's record.
- This is one reason some couples discuss claiming timing jointly rather than individually.
Taxes on benefits
- When combined income passes $25,000 (single) or $32,000 (joint), part of the benefit becomes federally taxable, up to 85% of it, per SSA. Those thresholds have never been indexed to inflation, so more retirees cross them every year. A few states tax benefits as well.
- The $6,000 senior deduction in the 2025 tax law (for people 65+, tax years 2025–2028, phasing out above $75,000 of income, or $150,000 joint) lowers taxable income, but it didn't make Social Security tax-free, per the IRS.
- The claiming age itself doesn't change these tax rules, but the size of the benefit — and other income arriving at the same time — can affect how much of it ends up taxable. A tax professional can help model this for a specific situation.
Needing the money now
- For some households, waiting simply isn't realistic if there's no other income to bridge the gap between stopping work and claiming later.
- There's no shame in this — it's a legitimate factor, not a mistake.
Common mistakes and myths
- Treating breakeven age as the whole decision. It's one useful data point, not a verdict — health, other income, and household needs regularly outweigh it.
- Assuming "Social Security is going away" and claiming purely out of that fear. The 2026 Trustees Report projects that if Congress does nothing, the combined trust funds run dry in 2034 — and incoming payroll taxes would still pay about 83% of scheduled benefits. A possible cut is a real planning risk; a system that stops paying isn't what the projections show. Claiming at 62 also doesn't shield anyone from a future across-the-board cut.
- Tying Medicare to claiming. Medicare eligibility starts at 65 no matter when Social Security starts. Someone delaying benefits past 65 isn't enrolled automatically and generally needs to sign up — unless covered by a current employer's health plan — or risk a permanent late-enrollment penalty on Part B.
- Forgetting the survivor benefit angle when one spouse earned significantly more — the higher earner's claiming age can shape what the survivor receives for decades.
- Not checking an actual personalized estimate. Everyone's earnings record is different, so the example above won't match anyone's real numbers.
- Ignoring the earnings test confusion. Some people avoid working after claiming early because they think withheld benefits are lost forever — they're not; they're factored back in later.
Tip
The SSA's my Social Security online account shows an estimate built from a person's actual earnings history, including projected benefits at 62, full retirement age, and 70. It's the most direct way to see real numbers instead of an example. For decisions involving spouses, survivor benefits, or taxes, a qualified financial or tax professional can help apply these rules to a specific situation.
FAQ
What exactly is the Social Security breakeven age?
It's the age at which the total cumulative dollars from claiming later catch up to and pass the total from claiming earlier, based on a given benefit estimate. It's a math concept, not a prediction of how long anyone will live.
Does claiming at 62 permanently lock in a lower benefit?
Yes. Under current Social Security Administration rules, claiming before full retirement age results in a permanent reduction to the monthly benefit, and claiming after full retirement age (up to 70) results in a permanent increase, as described on the [SSA's retirement planning page](https://www.ssa.gov/retirement/plan-for-retirement).
Is Social Security going to run out and stop paying benefits?
No. The Social Security Trustees' 2026 report projects that if Congress doesn't act, the combined trust funds are depleted in 2034, after which ongoing payroll taxes would still cover about 83% of scheduled benefits. Congress has changed the program's financing before, so the actual outcome depends on future law.
Can I change my claiming decision after I've started benefits?
SSA lets someone withdraw a benefit application once, within 12 months of approval, by repaying everything received. After full retirement age, benefits can also be voluntarily suspended to earn delayed retirement credits up to age 70.
Does working while collecting benefits before full retirement age reduce them forever?
No. If earnings trigger the [earnings test](https://www.ssa.gov/oact/cola/rtea.html) before full retirement age, the withheld amount isn't lost — SSA raises the monthly benefit at full retirement age to account for the months withheld.
Related reading
How much should you have saved for retirement by age?
Widely cited benchmarks suggest saving roughly 1x your salary by 30, 3x by 40, 6x by 50, and 10x by 67 — but the number that actually matters most is your savings rate, not a single checkpoint.
When can you actually retire? How to know if you're on track
Retiring isn't about hitting a birthday — it's about your savings, spending, and guaranteed income lining up so a sustainable withdrawal rate covers your life. Here's the math that actually answers the question.
How does a pension affect Social Security benefits?
For decades, two lesser-known rules could shrink or wipe out Social Security checks for teachers, police, firefighters, and other public workers with a pension. Both were repealed in 2025 — here's what changed and who it affects.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.