If a pension plan has offered a choice between a lump sum and a monthly check for life, there is no single right answer — it depends on health, other savings, risk tolerance, and what happens to the money after death. But the two options are not equivalent in value; they trade off differently on longevity, inflation, and flexibility, and understanding those trade-offs is the whole decision.
- A monthly annuity keeps longevity and investment risk with the pension plan; a lump sum shifts both risks to the retiree.
- Lump-sum offers are calculated using interest rate assumptions — when rates rise, the lump sum needed to fund the same monthly check generally shrinks, and vice versa.
- Most monthly pensions have no automatic inflation adjustment, while a self-managed lump sum can be invested to try to keep pace with rising prices.
- A federal insurance program backs many private pensions up to certain limits, but coverage rules and limits vary by plan type and don't apply to lump sums already paid out.
- Rolling a lump sum into an IRA or 401(k) generally defers taxes; taking it as cash usually triggers immediate income tax and withholding.
What each option actually is
A pension typically offers a version of two basic shapes: keep receiving income for life, or take one payment and manage it independently.
- Monthly annuity: an annuity paid by the pension plan, usually for as long as the retiree lives, calculated from years of service, salary history, and the plan's formula.
- Lump-sum buyout: a lump-sum buyout meant to represent the value today of that entire stream of future checks.
Once the choice is made, it is typically final. Many plans do not allow switching back from a lump sum to the monthly option, or vice versa, after the election is filed.
How the plan turns a monthly check into one lump number
A pension actuary estimates the lump sum by asking: how much money, invested today and earning a plan-assumed return, would be needed to fund every future monthly payment for as long as the retiree (and possibly a spouse) is expected to live?
- The calculation leans on interest rates. For most private-sector plans, federal law sets a floor on the lump sum using corporate bond rates the IRS publishes monthly, often called 417(e) rates.
- It also uses an IRS-prescribed mortality table, not the individual retiree's actual health. Someone in poor health gets the same offer as someone expecting to live to 100.
- When interest rates are higher, the plan assumes the lump sum can earn more on its own, so a smaller starting amount is treated as enough to fund the same monthly payments — the offer tends to be lower.
- When interest rates are lower, more principal is assumed necessary to produce the same future payments — the offer tends to be higher.
This is a general relationship, not a formula anyone outside the plan's actuaries can replicate precisely, and it means two people with identical pension benefits could see very different lump-sum offers depending on when they leave the job or elect the buyout.
Note
A lump-sum offer received this year and one received a few years earlier or later — for the exact same monthly benefit — can differ meaningfully simply because interest rates changed in between. Many plans lock their rates for a full plan year based on a lookback month set in the plan document, so the rate move shows up in next year's offer months before the letter arrives.
Tip
A sanity check planners use: get a quote from an insurer for a single-premium immediate annuity that pays the same monthly amount. If buying that same check on the open market would cost more than the lump sum on offer, the plan's annuity is the richer deal on paper — and the reverse is also true.
Where the risk goes
This is the heart of the decision: a lump sum does not eliminate risk, it transfers it.
- Longevity risk — the risk of outliving savings. With the monthly annuity, the plan keeps paying no matter how long the retiree lives. With a lump sum, the retiree's own money has to last, however long that turns out to be.
- Investment risk — the risk that returns fall short of what's needed. The monthly annuity's payment doesn't change based on how markets perform. A lump sum's ability to last depends entirely on how it's invested and how markets behave.
- Market timing at retirement — a downturn in the early years of drawing down a lump sum can do outsized damage compared with the same downturn hitting later, a pattern often called sequence-of-returns risk, because withdrawals lock in losses on money that no longer has time to recover.
The commonly cited "4% rule" comes from William Bengen's 1994 study in the Journal of Financial Planning, which found that a stock-and-bond portfolio historically survived at least 30 years when the first year's withdrawal was about 4% of the starting balance, raised for inflation each year after. It's also a useful yardstick here: a lump sum that has to pay out much more than 4% a year to match the pension is being asked to do something history says is hard. A monthly pension annuity sidesteps that withdrawal-rate question entirely, since the plan — not the retiree — is responsible for making the money last.
Inflation protection
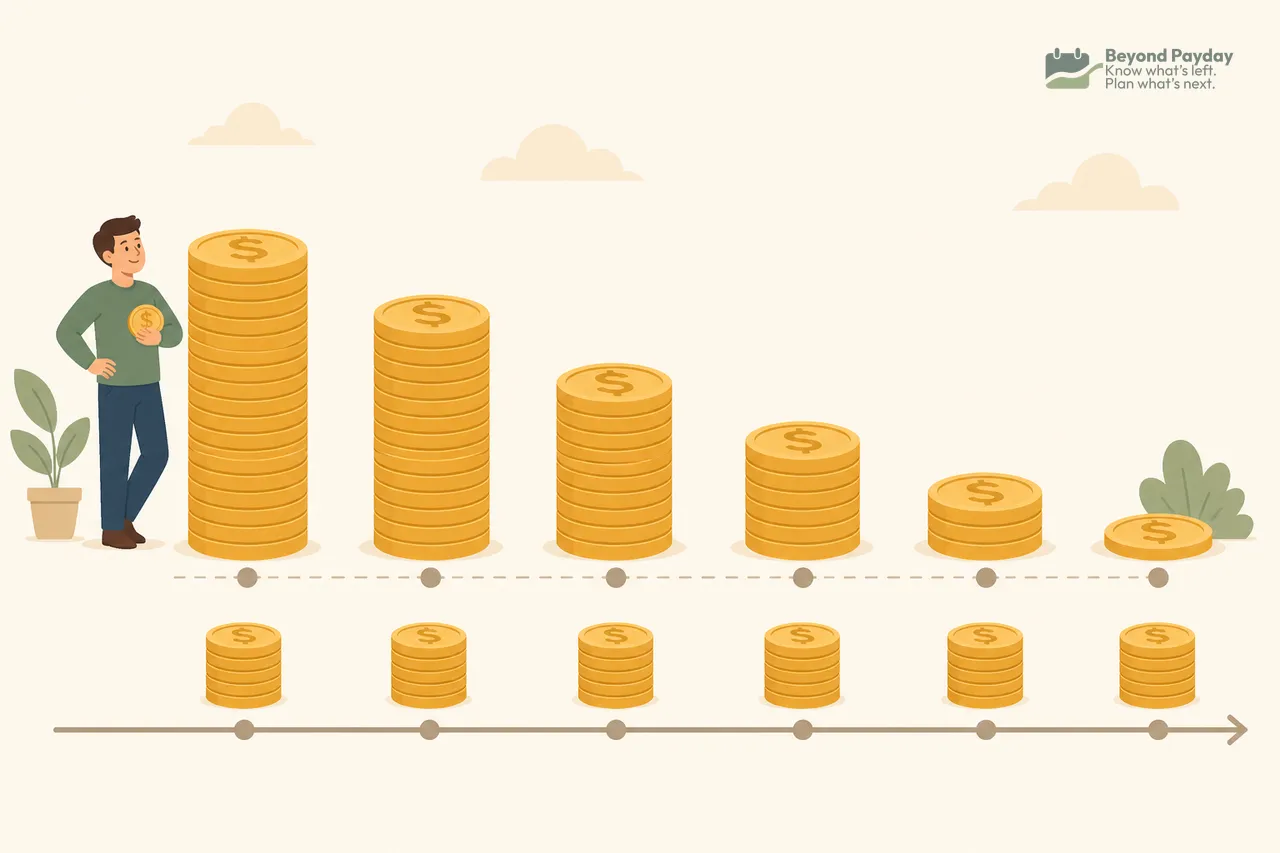
Most private pension annuities pay the same fixed dollar amount every month for life, with no adjustment for rising prices.
- A COLA is common in Social Security and some government pensions, but relatively uncommon in private-sector pension annuities.
- Without a COLA, a fixed monthly check buys noticeably less after 15–20 years of ordinary inflation, even at modest average inflation rates.
- A lump sum, invested and periodically adjusted, can grow enough to offset inflation over time, depending on how it's invested and how markets perform.
Survivor benefits
A monthly pension usually comes with a choice about what happens to payments after the retiree's death — a choice a lump sum handles very differently.
- A single-life annuity pays the largest monthly amount but stops entirely at the retiree's death, leaving nothing for a surviving spouse.
- A joint and survivor annuity pays less each month while both people are alive, but continues (often at 50%–100% of the original amount) for a surviving spouse.
- A lump sum sidesteps this trade-off differently: whatever is left when the retiree dies — whether that's most of it or none of it — simply passes to whoever is named as beneficiary or to the estate, with no reduction required while both spouses are alive.
- For a married participant, federal rules generally make the joint-and-survivor annuity the default. Choosing anything else — including the lump sum — typically requires the spouse's written, notarized (or plan-witnessed) consent.
The PBGC's role — and its limits
Many private-sector pensions are insured, but that insurance has real limits worth understanding before comparing it to a lump sum in hand.
- The PBGC steps in to pay a portion of promised benefits if a covered pension plan fails.
- Coverage generally applies to the ongoing monthly annuity benefit from covered private-sector plans — not to a lump sum that has already been paid out and put in the retiree's own account.
- Insured amounts have dollar caps that depend on age and benefit form. For single-employer plans ending in 2026, PBGC's maximum guarantee for a 65-year-old taking a straight-life annuity is $7,789.77 a month, and it's lower for younger retirees and survivor forms, per PBGC's 2026 tables. Most pensions fall well under the cap; large executive pensions sometimes don't.
- Multiemployer (union) plans are covered by a separate PBGC program with much lower guarantees.
- Government pensions (state, local, and federal) are not covered by PBGC at all.
In other words, keeping the monthly annuity generally carries some backstop if the employer or plan runs into trouble; a lump sum already in an IRA carries no such pension-specific insurance — its safety depends on how and where it's invested.
Rollover to an IRA vs. taking the cash
How a lump sum is received matters almost as much as the decision to take it.
- A rollover of the lump sum into a traditional IRA or another qualified employer plan generally keeps the money tax-deferred, meaning no income tax is due until money is later withdrawn (IRS: IRA-based retirement plans; IRS: 401(k) plans).
- Taking the lump sum directly as cash instead of rolling it over is generally treated as taxable income in the year received, often with mandatory withholding taken out immediately, and potentially pushing the recipient into a higher tax bracket for that year.
- A check paid to you comes with 20% federal withholding. It can still be rolled over within 60 days, but the missing 20% has to be made up from other money or it's taxed as a distribution, per the IRS. A direct rollover — plan pays the IRA — avoids the withholding entirely.
- Early-withdrawal tax: money taken before 59½ generally owes an extra 10%. One exception, for people who leave the employer in or after the year they turn 55 (50 for many public safety workers), applies to the employer plan but not to an IRA — so rolling everything to an IRA can switch off penalty-free access someone was counting on, per the IRS.
- None of this is a substitute for individual tax guidance — a CPA or tax professional can walk through how a specific rollover or cash-out would actually be taxed.
Watch out
Electing to receive a pension lump sum directly as a personal check, rather than as a direct rollover, can trigger immediate withholding and a large one-time tax bill — a costly mistake if the intent was actually to keep the money working for retirement.
Behavioral risk: a big number in one place
Even when the math is close, a large lump sum introduces a very human risk that a monthly annuity doesn't.
- A big balance is tempting. A six-figure account invites spending that a monthly check never would — a new roof, a child's emergency, a "sure thing" investment. Each can be reasonable on its own; together they can shorten how long the money lasts.
- Managing it takes ongoing discipline. A monthly annuity requires no investment decisions; a lump sum requires ongoing choices about allocation, withdrawal rate, and rebalancing, for decades.
- Fraud and pressure are real risks. A large one-time balance can attract unsolicited advice or sales pitches; a monthly check does not offer the same single point of exposure.
- Decision-making changes with age. A 2009 Brookings study by Agarwal, Driscoll, Gabaix and Laibson found that the quality of financial decisions tends to peak around age 53 and decline after. A lump sum needs active management into the 80s and 90s; an annuity doesn't.
Side-by-side comparison
| Monthly annuity | Lump-sum buyout | |
|---|---|---|
| Longevity risk | Held by the plan — payments continue for life | Held by the retiree — savings must last |
| Investment risk | Held by the plan | Held by the retiree |
| Inflation protection | Usually none, unless a COLA applies | None built in; depends entirely on how the money is invested |
| Backstop if plan fails | Often partly insured by PBGC, subject to limits | Not applicable — money is already out of the pension system |
| Flexibility | Fixed schedule, little to no access to extra cash | Full control over spending, investing, and timing |
| What heirs receive | Often nothing, unless a survivor or period-certain option was chosen | Any remaining balance generally passes to named beneficiaries |
| Spousal protection | Joint-and-survivor option available, usually requires spousal consent to waive | Handled through beneficiary designations instead |
| Tax timing | Taxed as ordinary income as each check arrives | Rollover defers tax; cash-out is generally taxed immediately |
| Reversibility | Typically a one-time, irrevocable election | Typically a one-time, irrevocable election |
An example with round numbers
Say a retiree is offered a single-life monthly pension annuity of $2,000 per month, or a lump-sum buyout of $300,000. Illustrative numbers.
Monthly annuity — total nominal dollars received (no COLA assumed), by how long the retiree lives:
| Years lived in retirement | Total received from annuity |
|---|---|
| 15 years | $360,000, then payments stop |
| 25 years | $600,000, then payments stop |
| 35 years | $840,000, then payments stop |
Lump sum: the $300,000 is invested and grows at an assumed average return of 5% per year, while $24,000 a year ($2,000/month) is withdrawn to match the annuity payment. Using this simplified annual model (withdraw, then apply growth to what remains), the balance runs out partway through year 19 of retirement. Put another way, a $300,000 lump sum for a $24,000-a-year pension is an 8% payout — double the 4% yardstick above.
| Years lived in retirement | What happens to the lump sum |
|---|---|
| 15 years | About $79,900 remains — available to heirs or for other use |
| 25 years | Exhausted around year 18–19; about 6–7 years with no income left from this source |
| 35 years | Exhausted around year 18–19; about 16 years with no income left from this source |
Assumptions and limits of this example: a flat 5% average annual return, no fees, no taxes, no inflation adjustment to the $2,000 withdrawal, and no market volatility — Real returns swing year to year, and a downturn early in retirement (sequence-of-returns risk) drains a balance faster than this model shows. The SEC's compound interest calculator tests other assumptions.
Tip
Because plan formulas, interest rate assumptions, survivor options, and insurance coverage all vary by employer and plan type, a fee-only fiduciary advisor or CPA who can review the actual pension plan documents is generally the right resource for a real decision — not a generic rule of thumb.
A pension choice is one piece of the bigger retirement picture — it only makes sense next to Social Security, savings, and the spending it has to cover.
FAQ
Is a pension lump sum offer negotiable?
Generally no. The amount is calculated using the plan's formula, current interest rate assumptions, and life expectancy tables, and most plans present it as a fixed take-it-or-leave-it figure.
Do I owe taxes if I take a pension lump sum in cash?
Taking a lump sum as cash instead of rolling it over generally makes it taxable as ordinary income in the year received, and the plan must withhold 20% for federal tax. A 10% early-withdrawal tax can also apply before 59½ unless an exception fits, per the [IRS](https://www.irs.gov/retirement-plans/plan-participant-employee/rollovers-of-retirement-plan-and-ira-distributions).
Can I roll a pension lump sum into a Roth IRA?
Pension lump sums are typically rolled into a traditional IRA first since the money hasn't been taxed yet; moving pre-tax pension money into a Roth account instead involves paying income tax on the converted amount, a decision usually made with a tax professional.
What happens to my pension if my former employer goes bankrupt?
Most private-sector defined benefit pensions are insured by the Pension Benefit Guaranty Corporation (PBGC) up to age-based limits — $7,789.77 a month at 65 for single-employer plans ending in 2026. Government pensions are not PBGC-insured.
Does a lump sum offer ever get better if I wait?
It depends mostly on interest rates: when rates fall, lump sums tend to rise, and when rates rise, they tend to shrink. Many plans set the rate for a full year from a lookback month, so recent rate moves hint at the direction of the next offer.
Related reading
How does a pension affect Social Security benefits?
For decades, two lesser-known rules could shrink or wipe out Social Security checks for teachers, police, firefighters, and other public workers with a pension. Both were repealed in 2025 — here's what changed and who it affects.
When can you actually retire? How to know if you're on track
Retiring isn't about hitting a birthday — it's about your savings, spending, and guaranteed income lining up so a sustainable withdrawal rate covers your life. Here's the math that actually answers the question.
Social Security at 62 vs. 67 vs. 70: how to think about it
Claiming Social Security early permanently shrinks your monthly check; waiting permanently grows it. Here's how the math, the breakeven age, and the personal factors actually fit together.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.