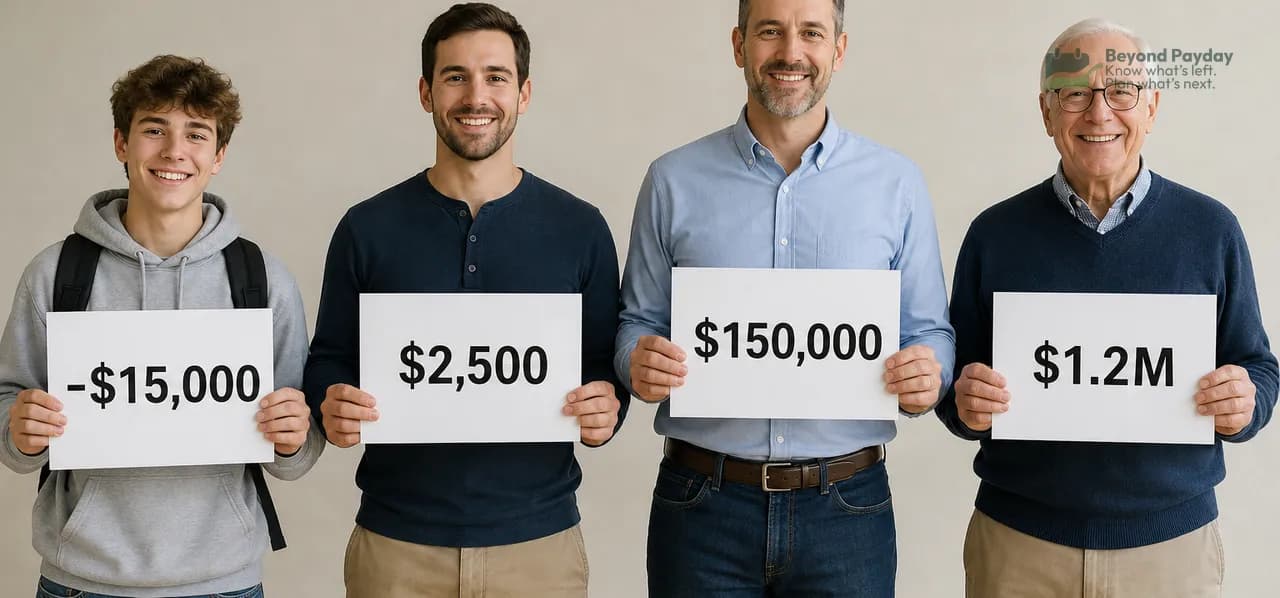
Net worth is what you own minus what you owe — every asset added up, minus every liability, at a single point in time. It's the one number that sums up your entire financial picture, whether you're 22 with student loans or 62 with a paid-off house.
- Net worth = total assets − total liabilities. That's the entire formula.
- It's a snapshot, not a speed — it tells you where you stand, not why you got there.
- Include everything you own (cash, investments, property, vehicles) and everything you owe (loans, credit cards, mortgages).
- A negative net worth early in adulthood is common and not automatically a warning sign.
- The trend over months and years matters more than any single number.
The formula, in plain terms
Net worth = Assets − Liabilities
- A asset is anything you own that's worth money.
- A liability is anything you owe money on.
Subtract the second from the first and you have a single number that represents your entire financial position — not your income, not your savings account balance, all of it netted together.
What counts as an asset
List everything with real resale or cash value:
- Cash and cash equivalents — checking, savings, money market accounts.
- Investments — brokerage accounts, individual stocks, index funds, bonds.
- Retirement accounts — 401(k), 403(b), traditional and Roth IRAs, pensions with a cash value.
- Real estate — the current market value of your home or any property you own, not what you paid for it.
- Vehicles — current resale value (check a valuation guide), not the sticker price.
- Business ownership — your stake in a business, if it has real resale value.
- Other valuables — collectibles, jewelry, or anything else with a genuine, verifiable resale market.
What counts as a liability
List every dollar you owe, regardless of the interest rate or how "good" the debt is considered:
- Mortgage balance — the amount left to pay, not the original loan amount.
- Auto loans
- Student loans
- Credit card balances — the amount carried past the due date, not your credit limit.
- Personal loans and lines of credit
- Any other debt — medical bills on a payment plan, money owed to family, buy-now-pay-later balances.
How to calculate yours in four steps
- List every asset and its current value — use statements, not guesses, wherever you can.
- List every liability and its current balance, not the original loan amount.
- Add up each list separately, then subtract total liabilities from total assets.
- Write down the date next to the result — a single number means little without a timeline to compare it to later.
An example with real numbers
Here's an illustrative snapshot for one hypothetical household:
| Assets | Value |
|---|---|
| Checking + savings | $8,000 |
| Brokerage account | $22,000 |
| 401(k) | $45,000 |
| Car (resale value) | $12,000 |
| Home (market value) | $310,000 |
| Total assets | $397,000 |
| Liabilities | Balance |
|---|---|
| Credit card balance | $3,000 |
| Auto loan | $9,000 |
| Student loans | $18,000 |
| Mortgage balance | $260,000 |
| Total liabilities | $290,000 |
Net worth = $397,000 − $290,000 = $107,000.
Notice that the home is the largest asset and the mortgage is the largest liability — for most homeowners, home equity (the gap between the two) makes up a large share of total net worth.
Why net worth beats income or a bank balance as "the" number
- Income measures cash flow, not wealth. A high earner with high spending and high debt can have a lower net worth than a modest earner who saves consistently.
- A bank balance ignores debt entirely. $20,000 in savings looks very different next to $0 in debt than next to $80,000 in credit card balances.
- Net worth nets everything together, which is exactly why it's the hardest number to fake and the most complete single measure of financial position.
Tip
Net worth is a snapshot, not a verdict. A student with $150,000 in future earning power and $40,000 in loans has a very different trajectory than the number alone suggests.
Common mistakes to avoid
- Using purchase price instead of resale value for cars, electronics, or furniture — these depreciate fast, and counting them at what you paid overstates your assets.
- Forgetting small debts — a $2,000 buy-now-pay-later balance or an old medical bill still counts.
- Counting home value without the mortgage, or vice versa — both numbers matter; only the gap between them (equity) is the actual asset value to your net worth.
- Recalculating too often and reacting to noise — investment and home values move week to week; a monthly or quarterly cadence shows the real trend without the whiplash.
- Getting discouraged by a negative number — many people in their 20s have negative net worth because of student loans and no assets yet. It's a starting line, not a grade.
FAQ
Is a negative net worth bad?
Not necessarily. It's common in your 20s and early 30s due to student loans, a car loan, or a new mortgage with little equity yet. What matters more is the trend over time.
Does net worth include my salary or paycheck?
No. Net worth is a snapshot of what you own and owe at one moment — income is a flow of money, not a stockpile of it. A high salary doesn't guarantee a high net worth, and vice versa.
Should I count my car as an asset?
Yes, at its realistic resale value, not what you paid for it. Most cars lose value every year, so update the estimate periodically rather than using the purchase price indefinitely.
How often should I recalculate my net worth?
Monthly or quarterly is common for tracking progress without over-reacting to normal market swings. Annually is the minimum to catch meaningful trends.
Does net worth include retirement accounts?
Yes — 401(k)s, IRAs, and similar accounts count as assets at their current balance. Some people choose to note that traditional (pre-tax) balances will owe income tax on withdrawal, but most net worth calculations use the full current balance.
Sources and context
These primary publications explain the data and concepts identified below. Survey results and historical examples describe their stated populations and periods; they do not predict an individual outcome.
- Federal Reserve: 2022 Survey of Consumer Finances
Household assets, debts, and median versus mean net worth by age; figures are for the 2022 survey.
Related reading
What's the average net worth by age?
Average net worth by age varies wildly depending on whether you look at the mean or the median. Here's why that gap matters and rough, survey-based figures by decade.
How to increase your net worth
Net worth grows two ways: build assets and shrink liabilities. Here are the actual levers that move the number, in the order they tend to matter most.
Assets vs liabilities: what actually counts?
An asset is what you own, a liability is what you owe — but real life has gray areas: cars, houses, and "good debt" all complicate the simple version.
Beyond Payday is a planning tool, not a financial advisor. This article is educational — projections and examples are estimates, not financial, tax, or investment advice.